Download

EVR Global Expansion Dossier

EVR▼ CONFIDENTIAL BOARD MOTORS GLOBAL EXPANSION DOSSIER AUGUST STRATEGY / THE COST OF BEING 2026 RIGHT Where EVR enters next, in what order, and what a wrong call costs. EVR does not have a market-size problem. It has a sequencing problem. The topology already wins on the merits; the value at risk…
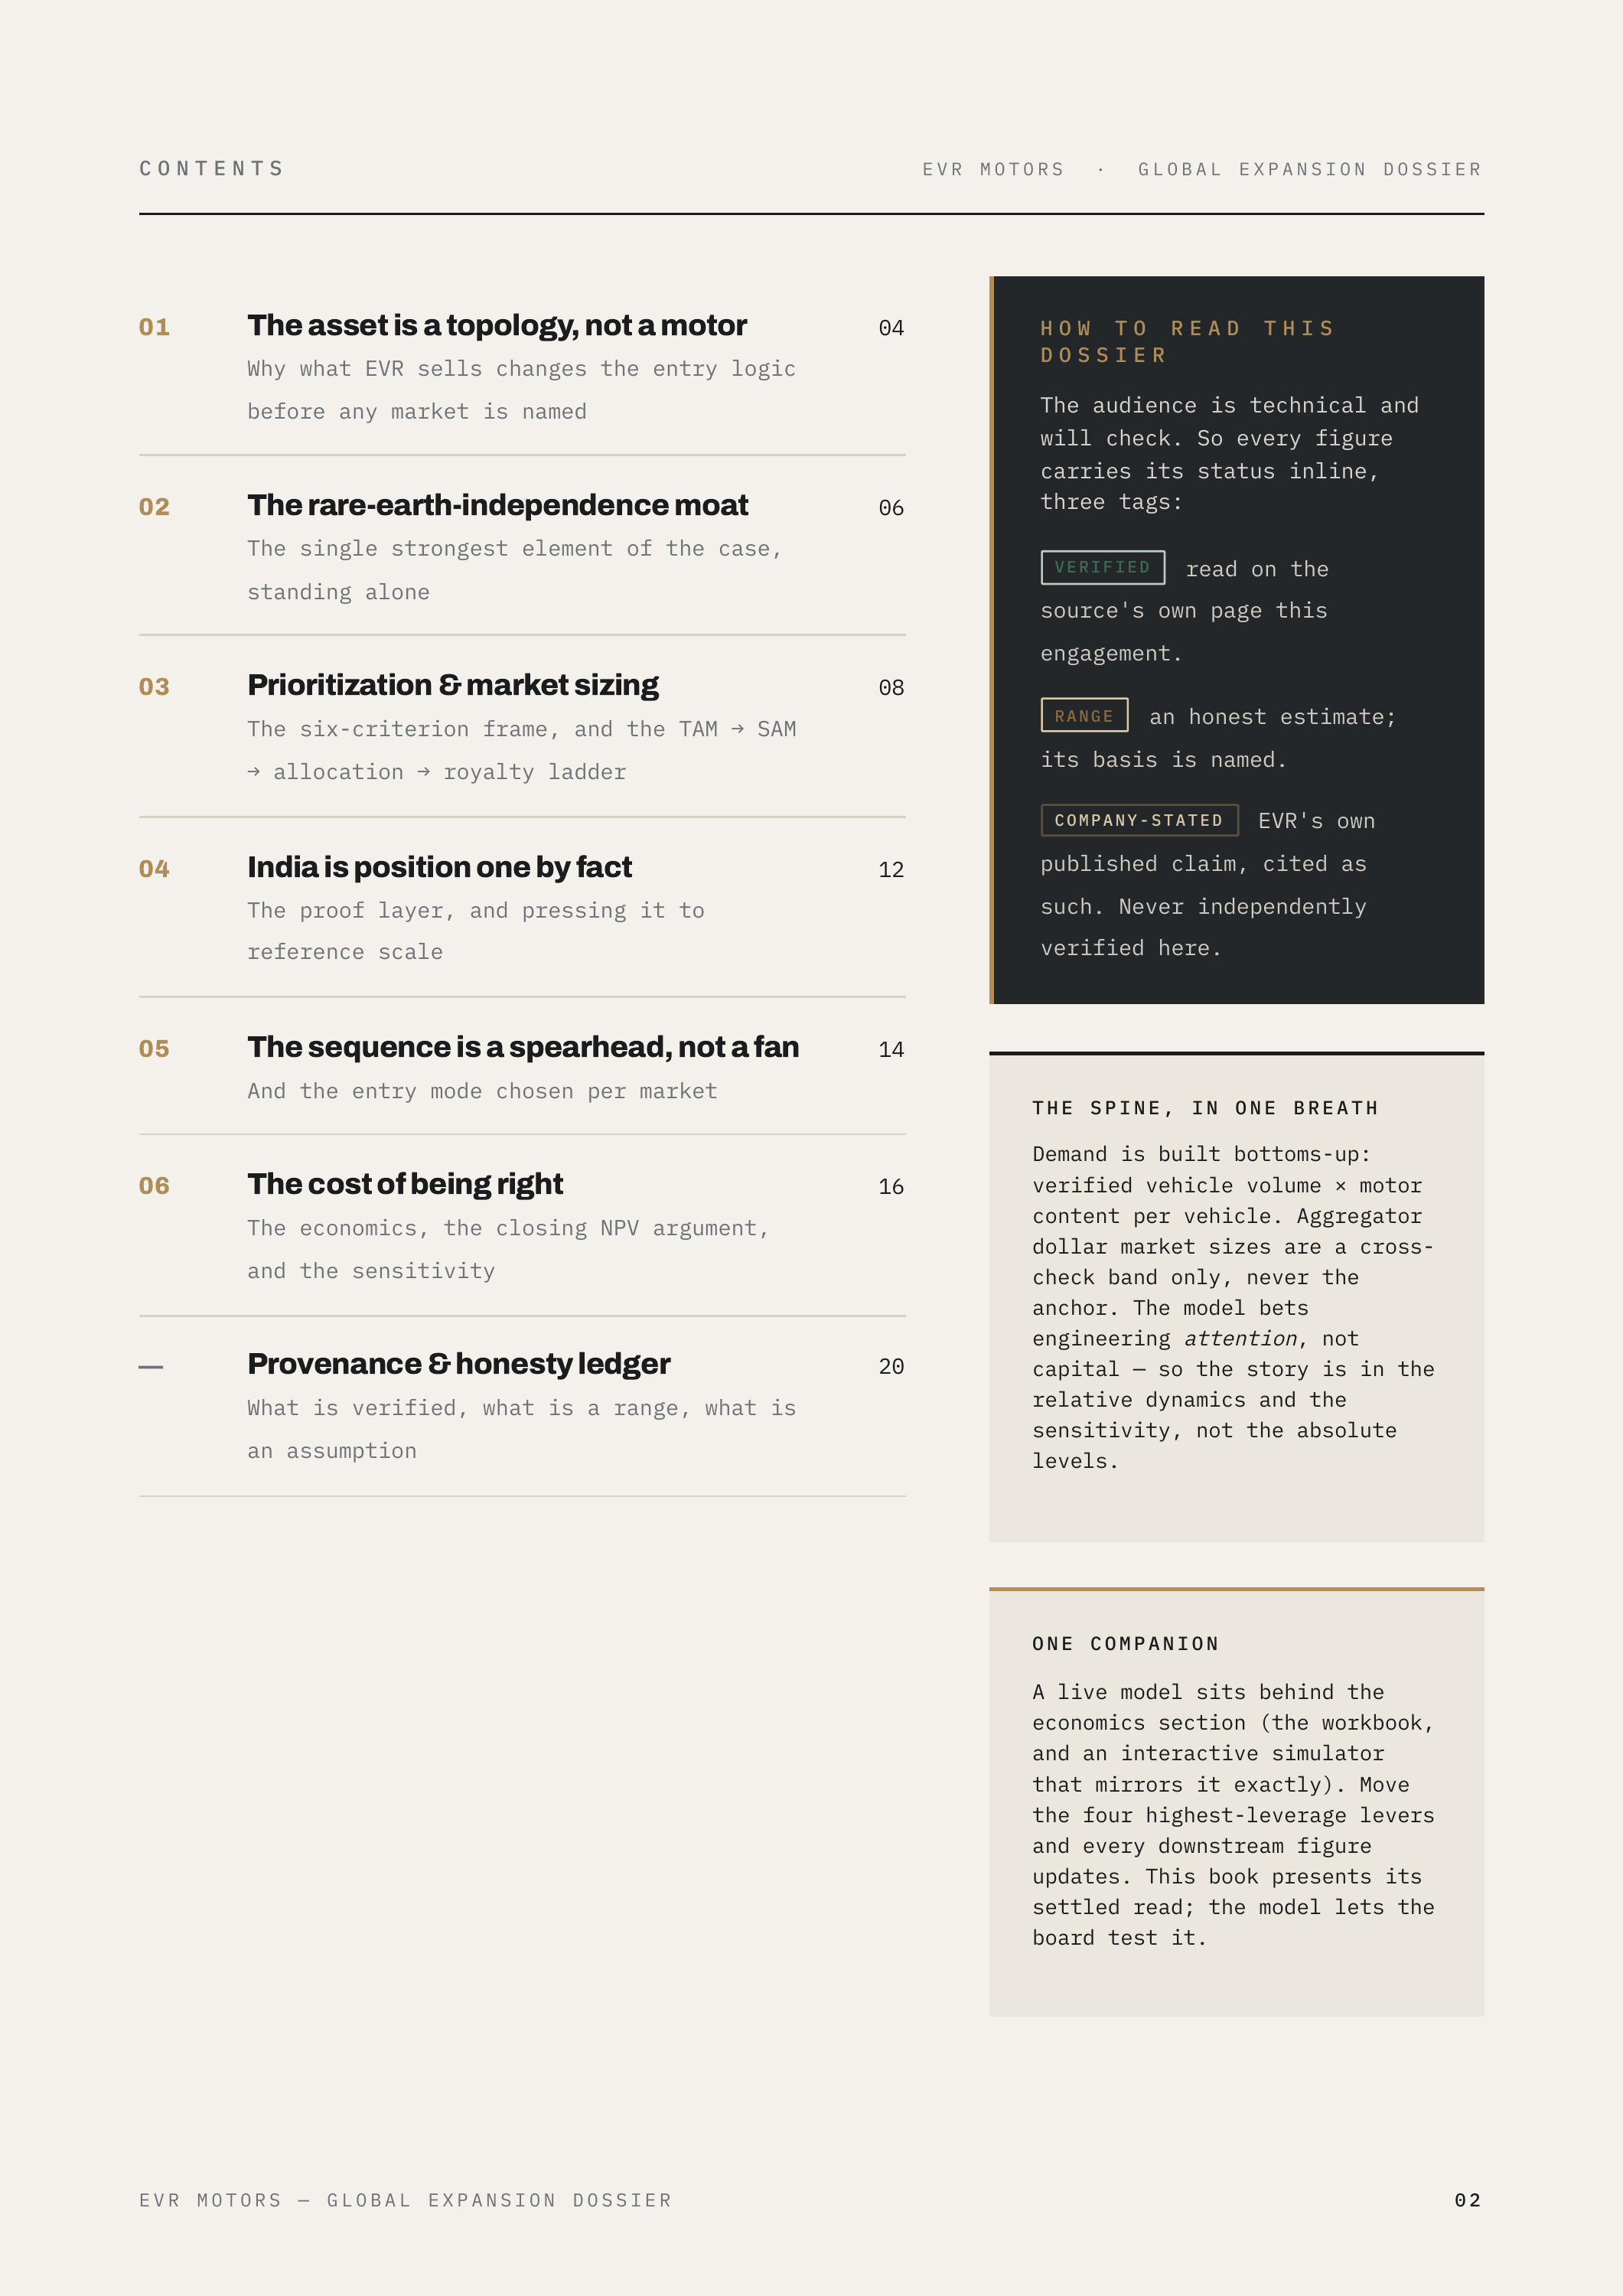
CONTENTS 01 The asset is a topology, not a motor EVR MOTORS 04 Why what EVR sells changes the entry logic The rare-earth-independence moat 06 read on the source's own page this engagement. 08 RANGE The six-criterion frame, and the TAM → SAM an honest estimate; its basis is named. → allocation →…
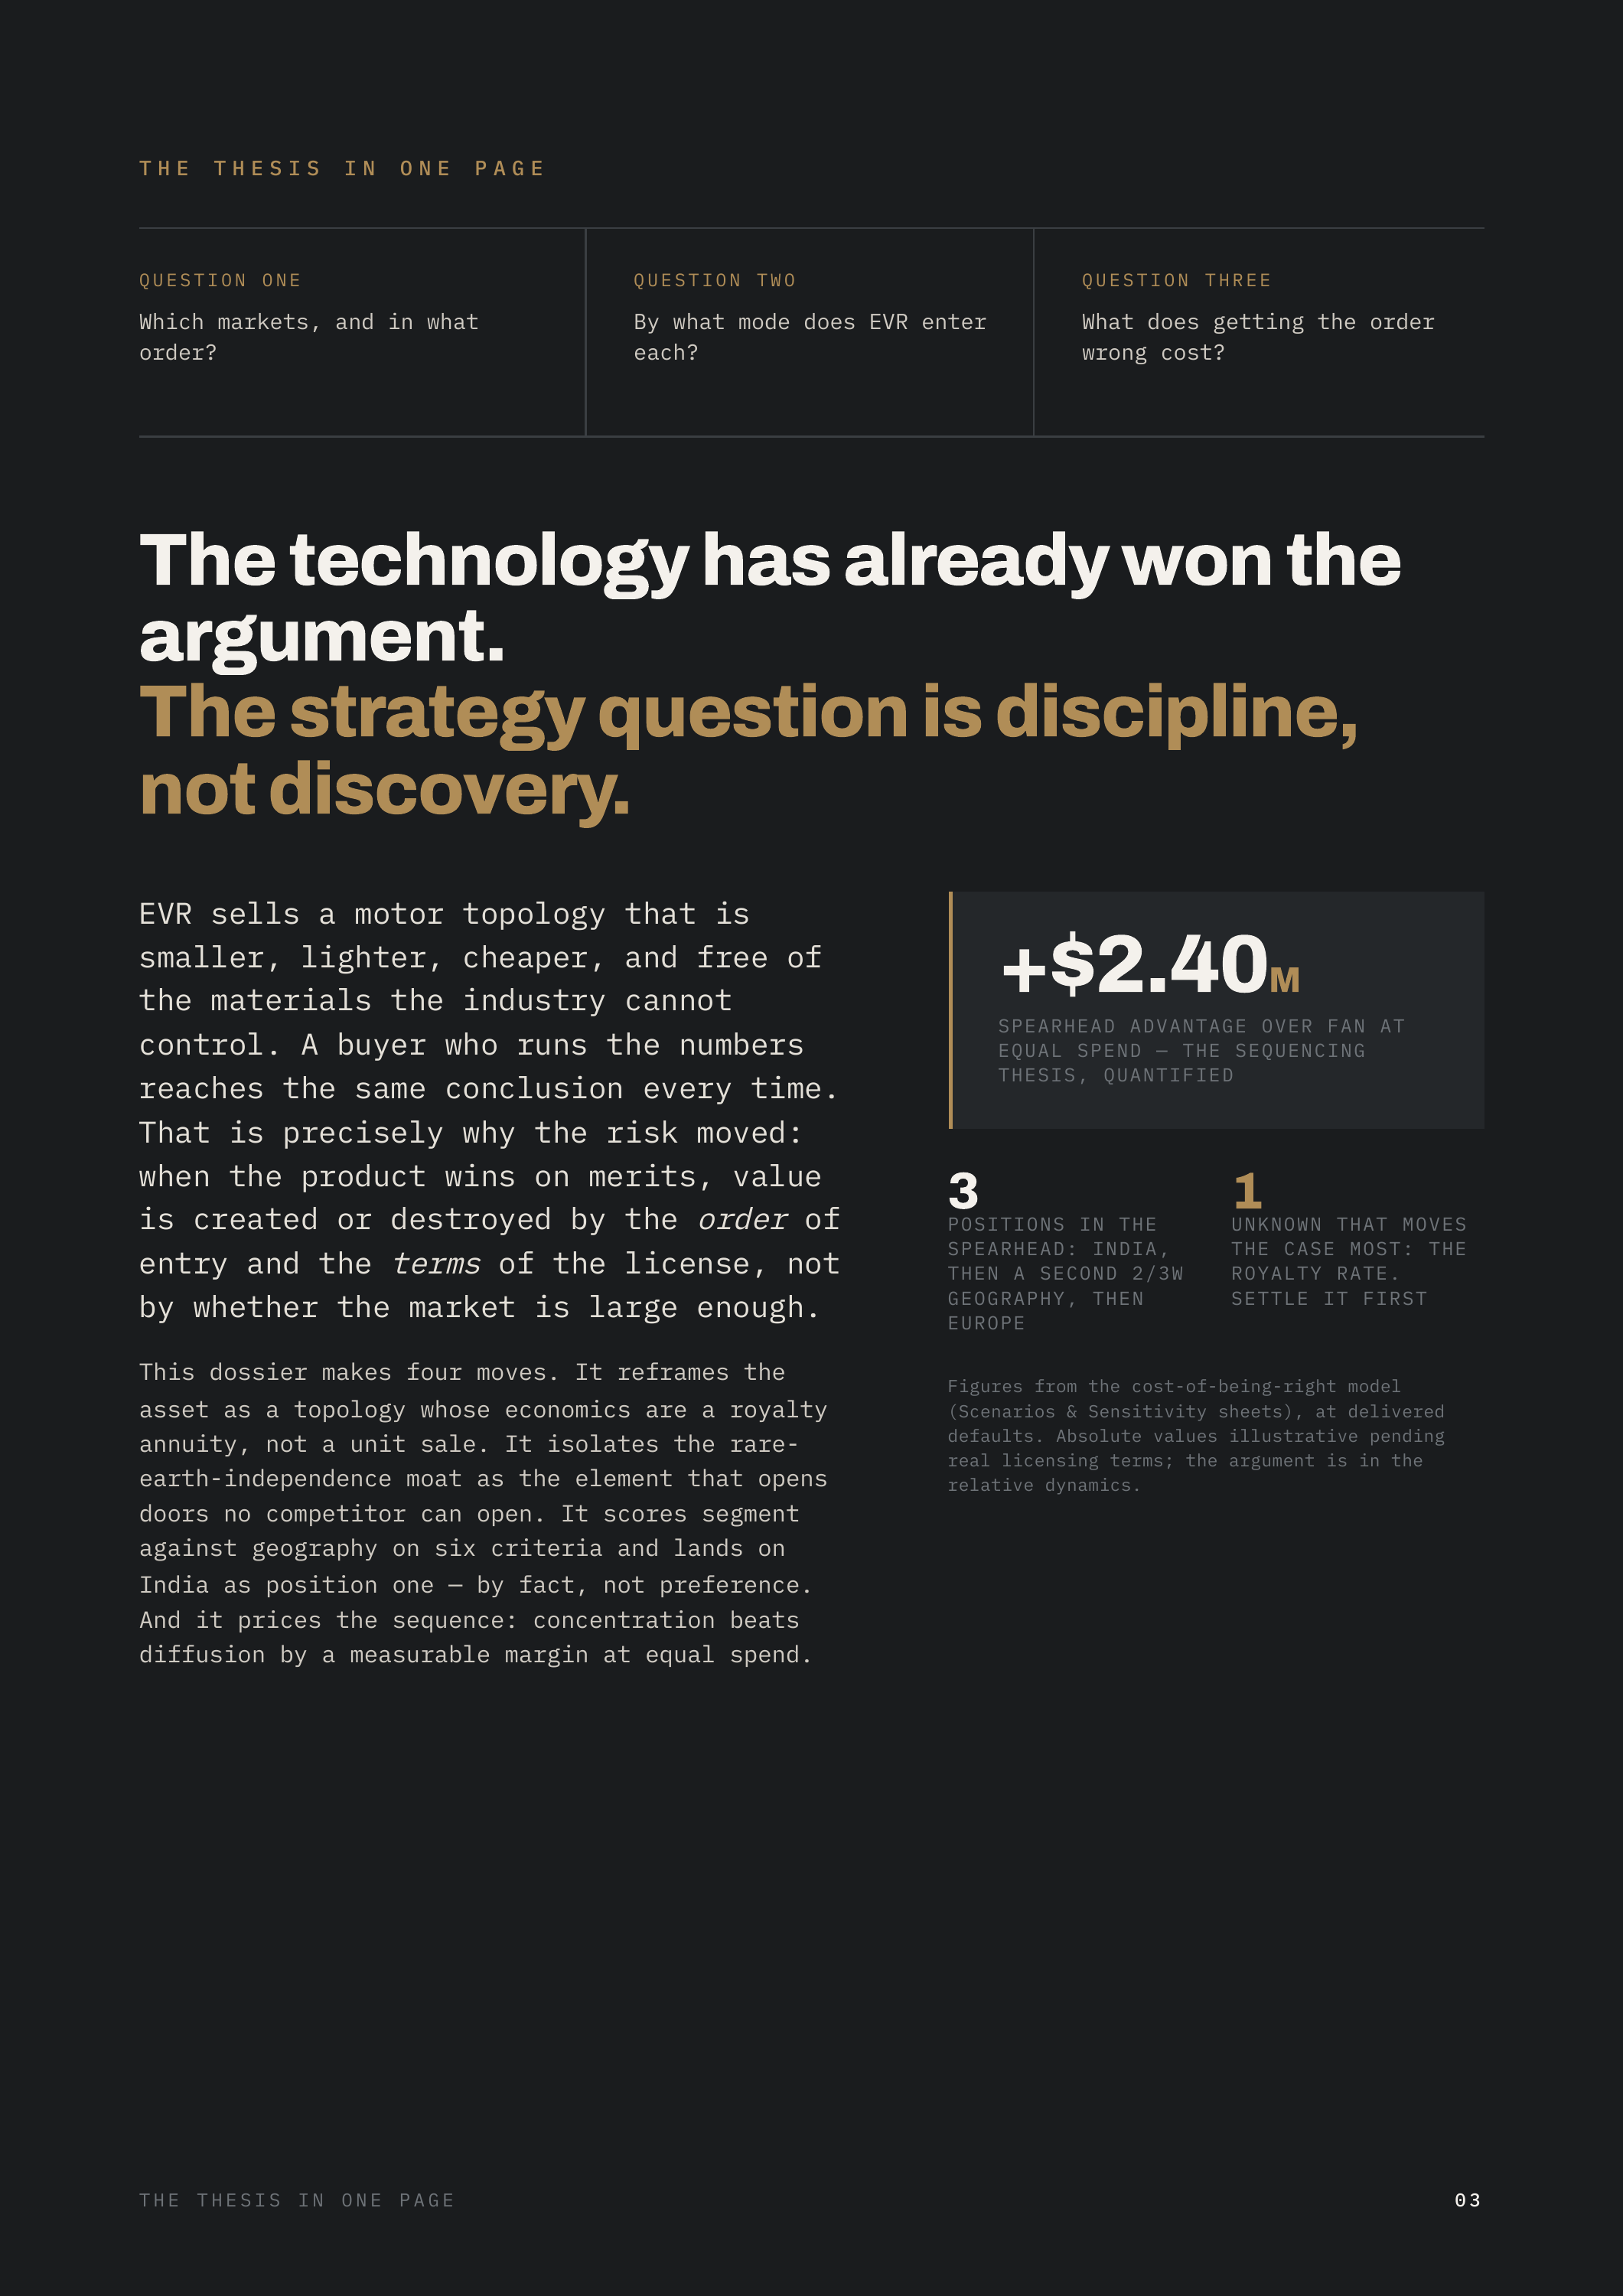
THE THESIS IN ONE PAGE QUESTION ONE QUESTION TWO QUESTION THREE Which markets, and in what order? By what mode does EVR enter each? What does getting the order wrong cost? The technology has already won the argument. The strategy question is discipline, not discovery. +$2.40M EVR sells a motor…
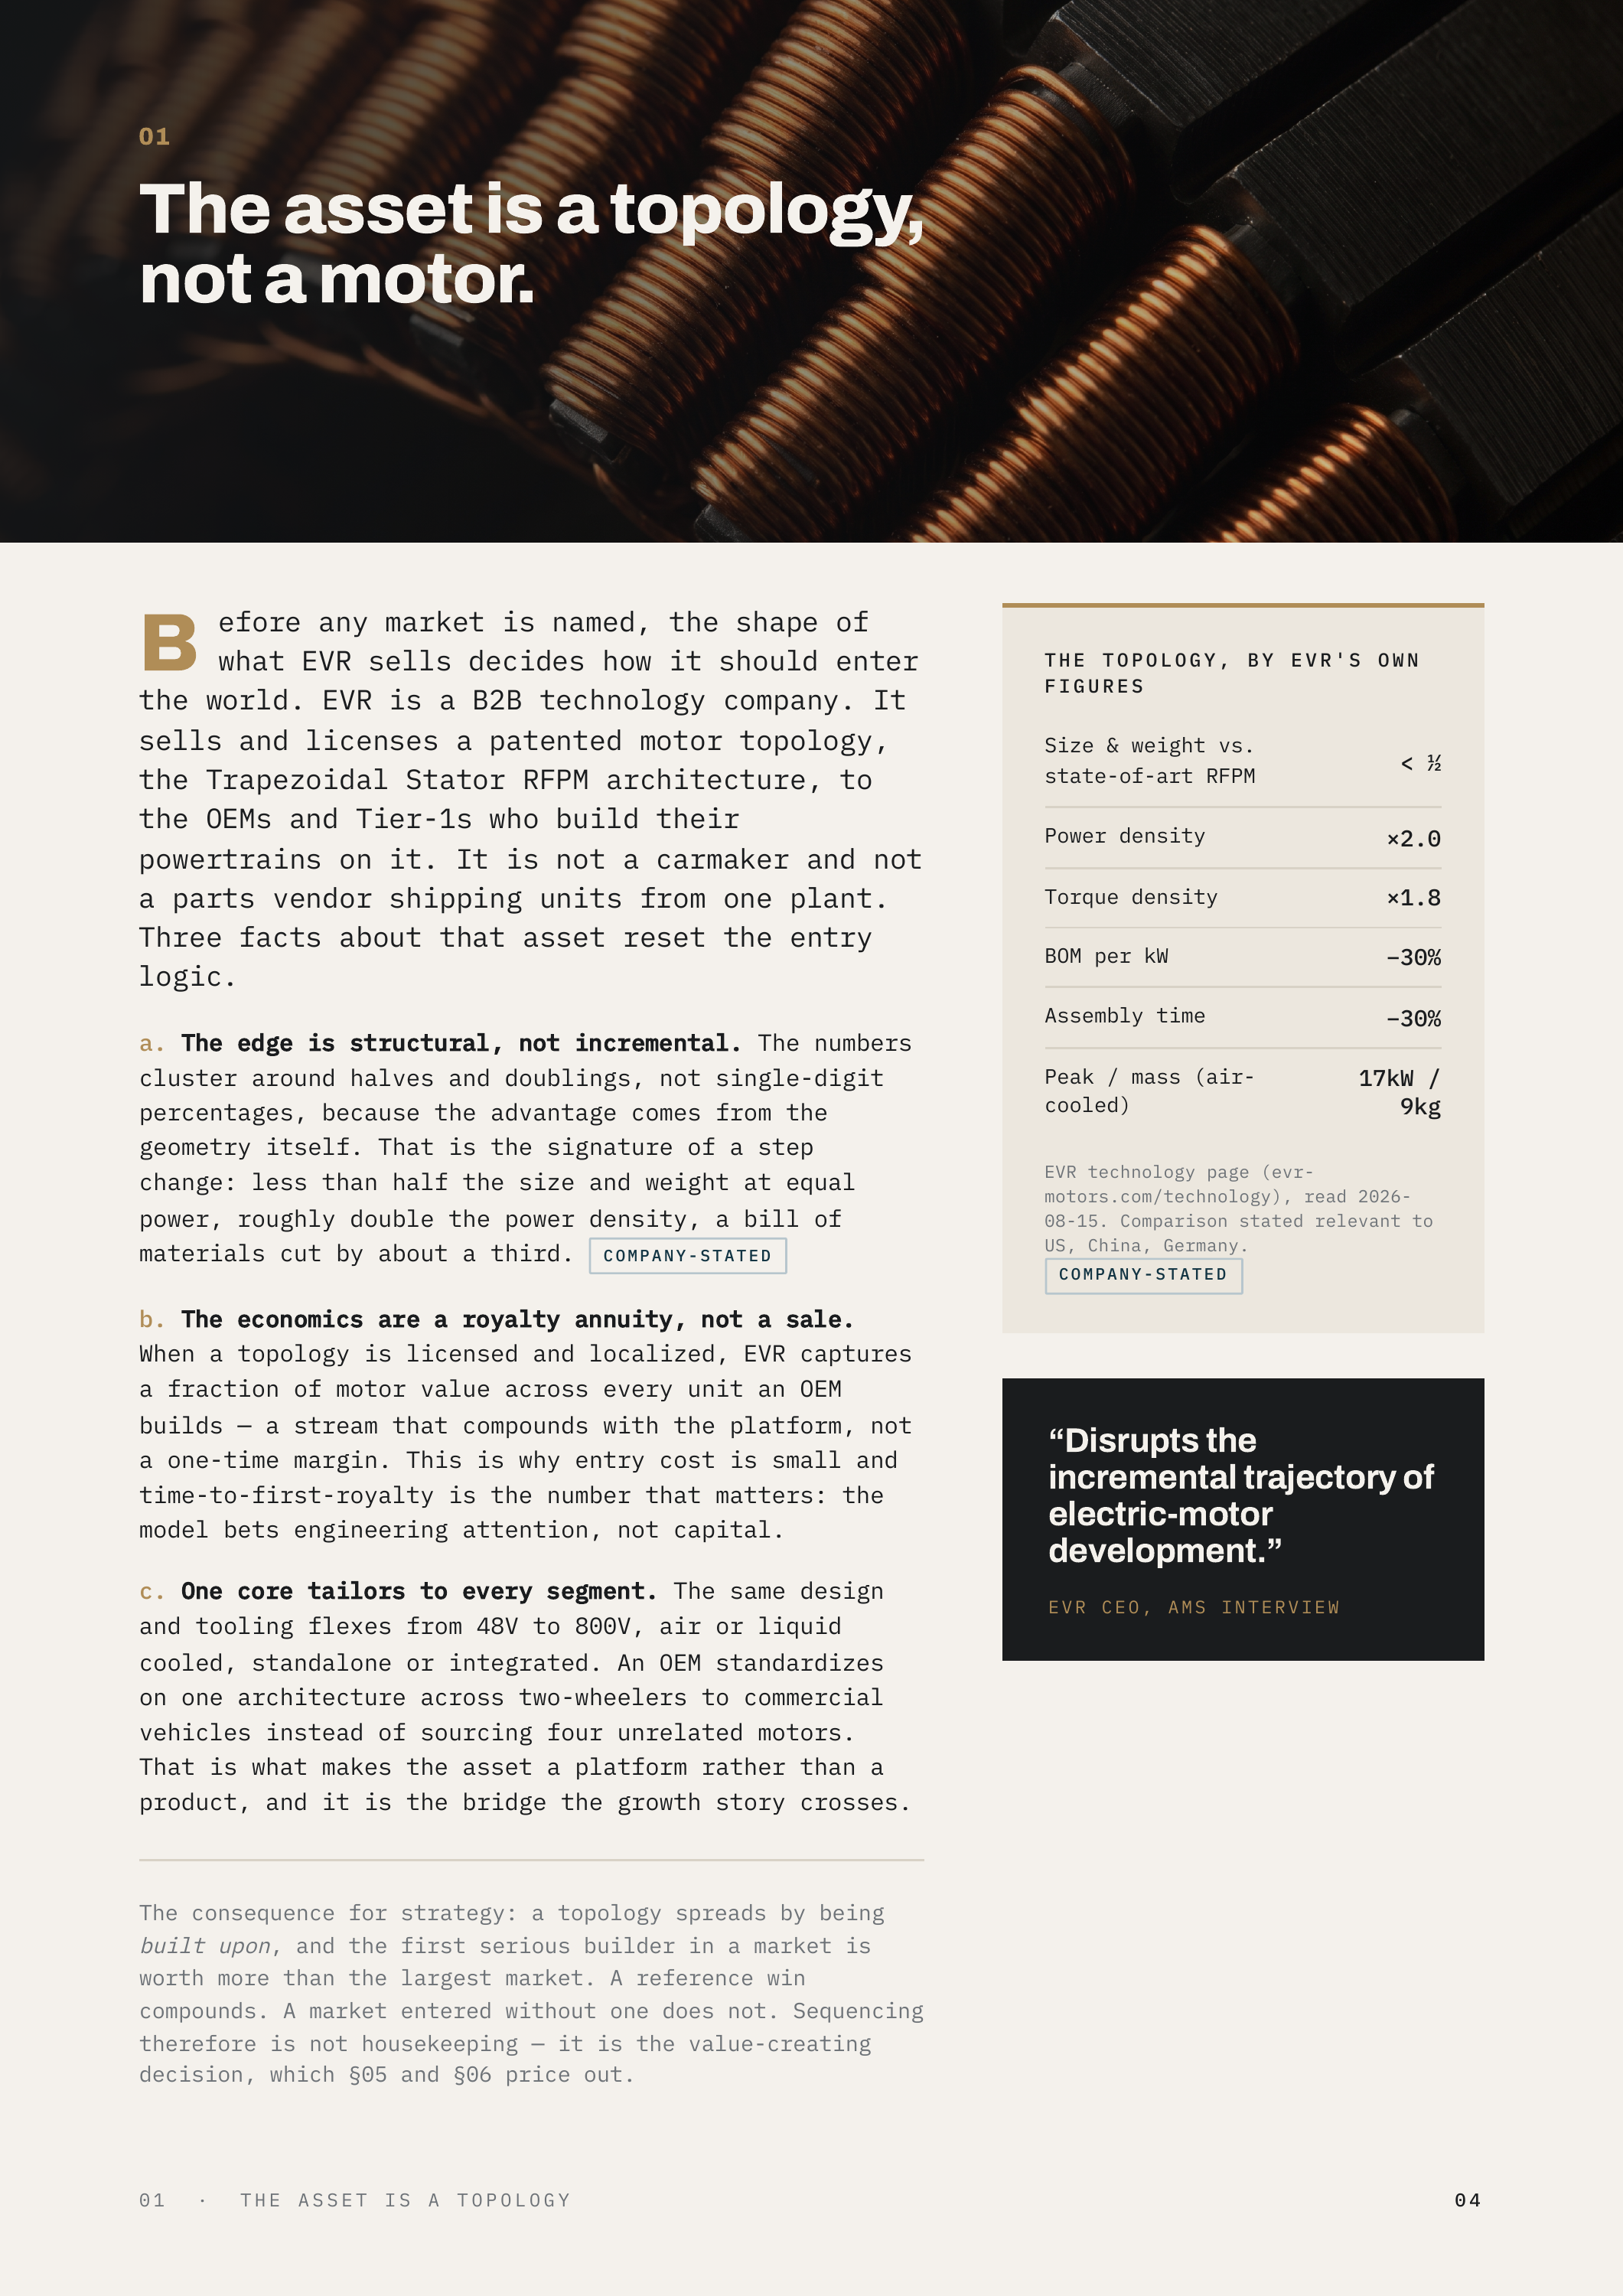
01 The asset is a topology, not a motor. B efore any market is named, the shape of what EVR sells decides how it should enter the world. EVR is a B2B technology company. It sells and licenses a patented motor topology, the Trapezoidal Stator RFPM architecture, to the OEMs and Tier-1s who build…
02 The rare-earthindependence moat. This is the single strongest element of the case, so it stands alone. Every other advantage helps EVR win a bake-off it was invited to. This one gets EVR invited. WHAT HAPPENED In April 2025, China tightened export controls on seven heavy rare-earth elements and…
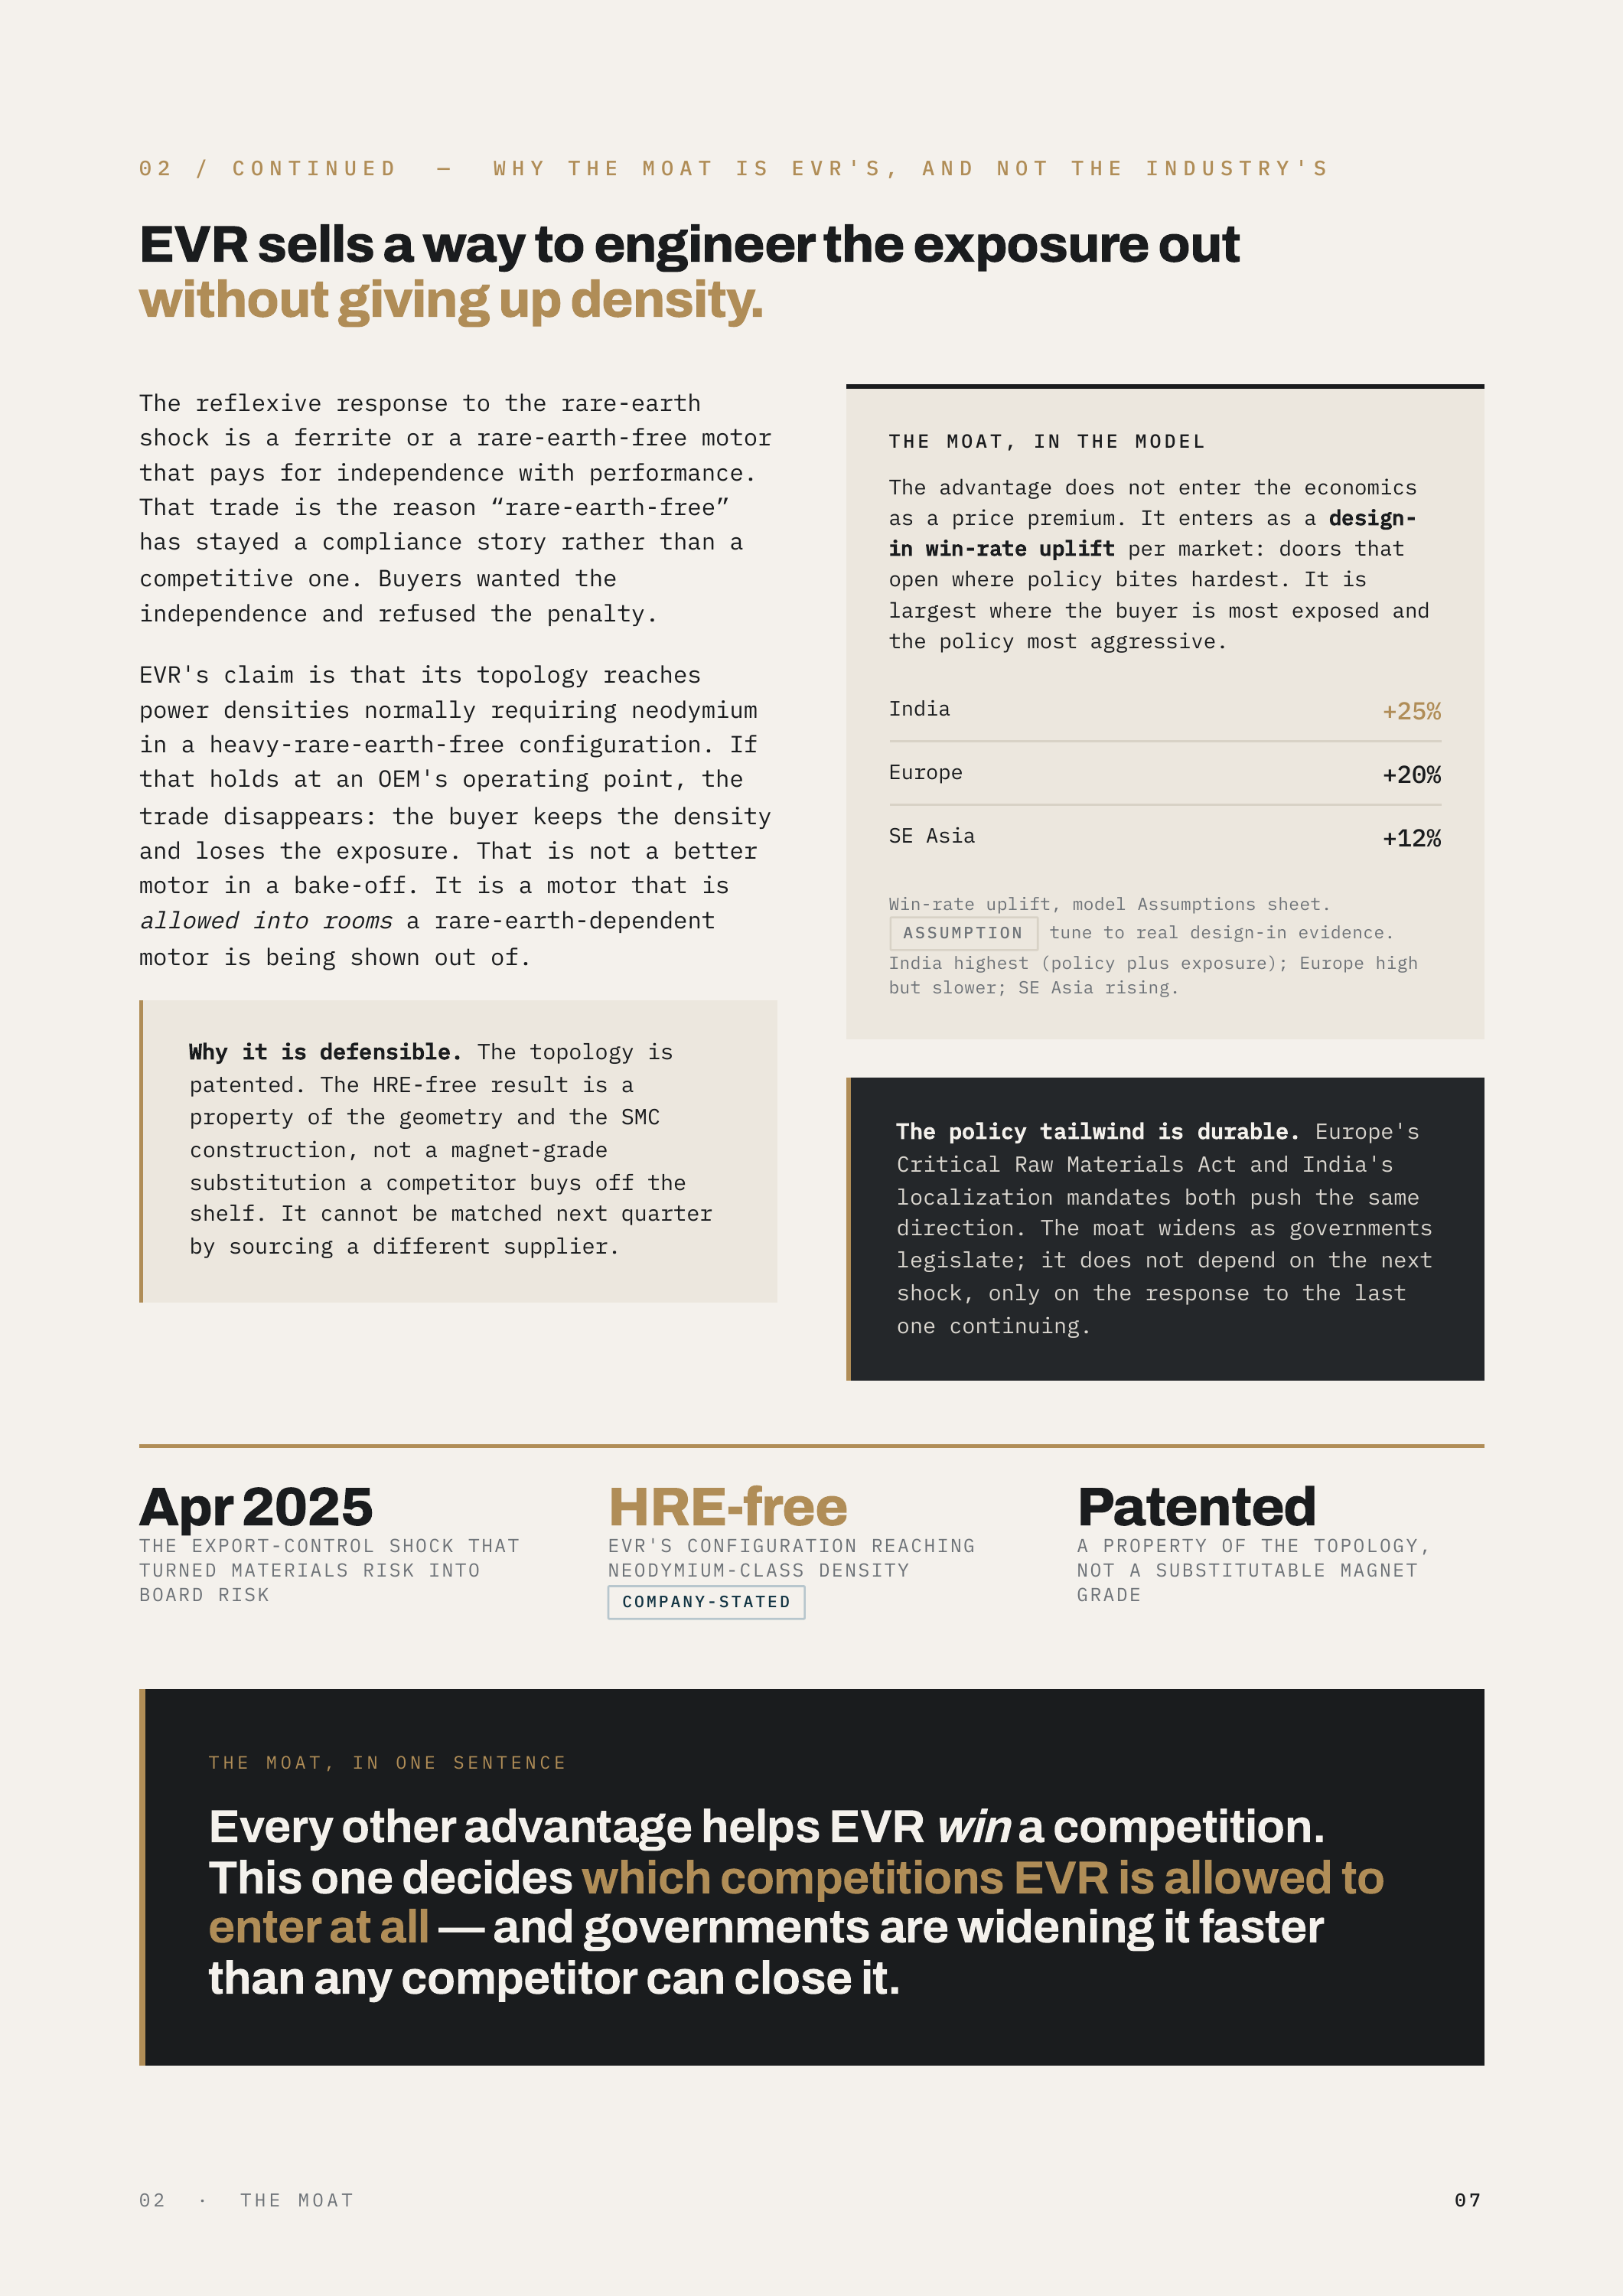
02 / CONTINUED — WHY THE MOAT IS EVR'S, AND NOT THE INDUSTRY'S EVR sells a way to engineer the exposure out without giving up density. The reflexive response to the rare-earth shock is a ferrite or a rare-earth-free motor that pays for independence with performance. That trade is the reason…
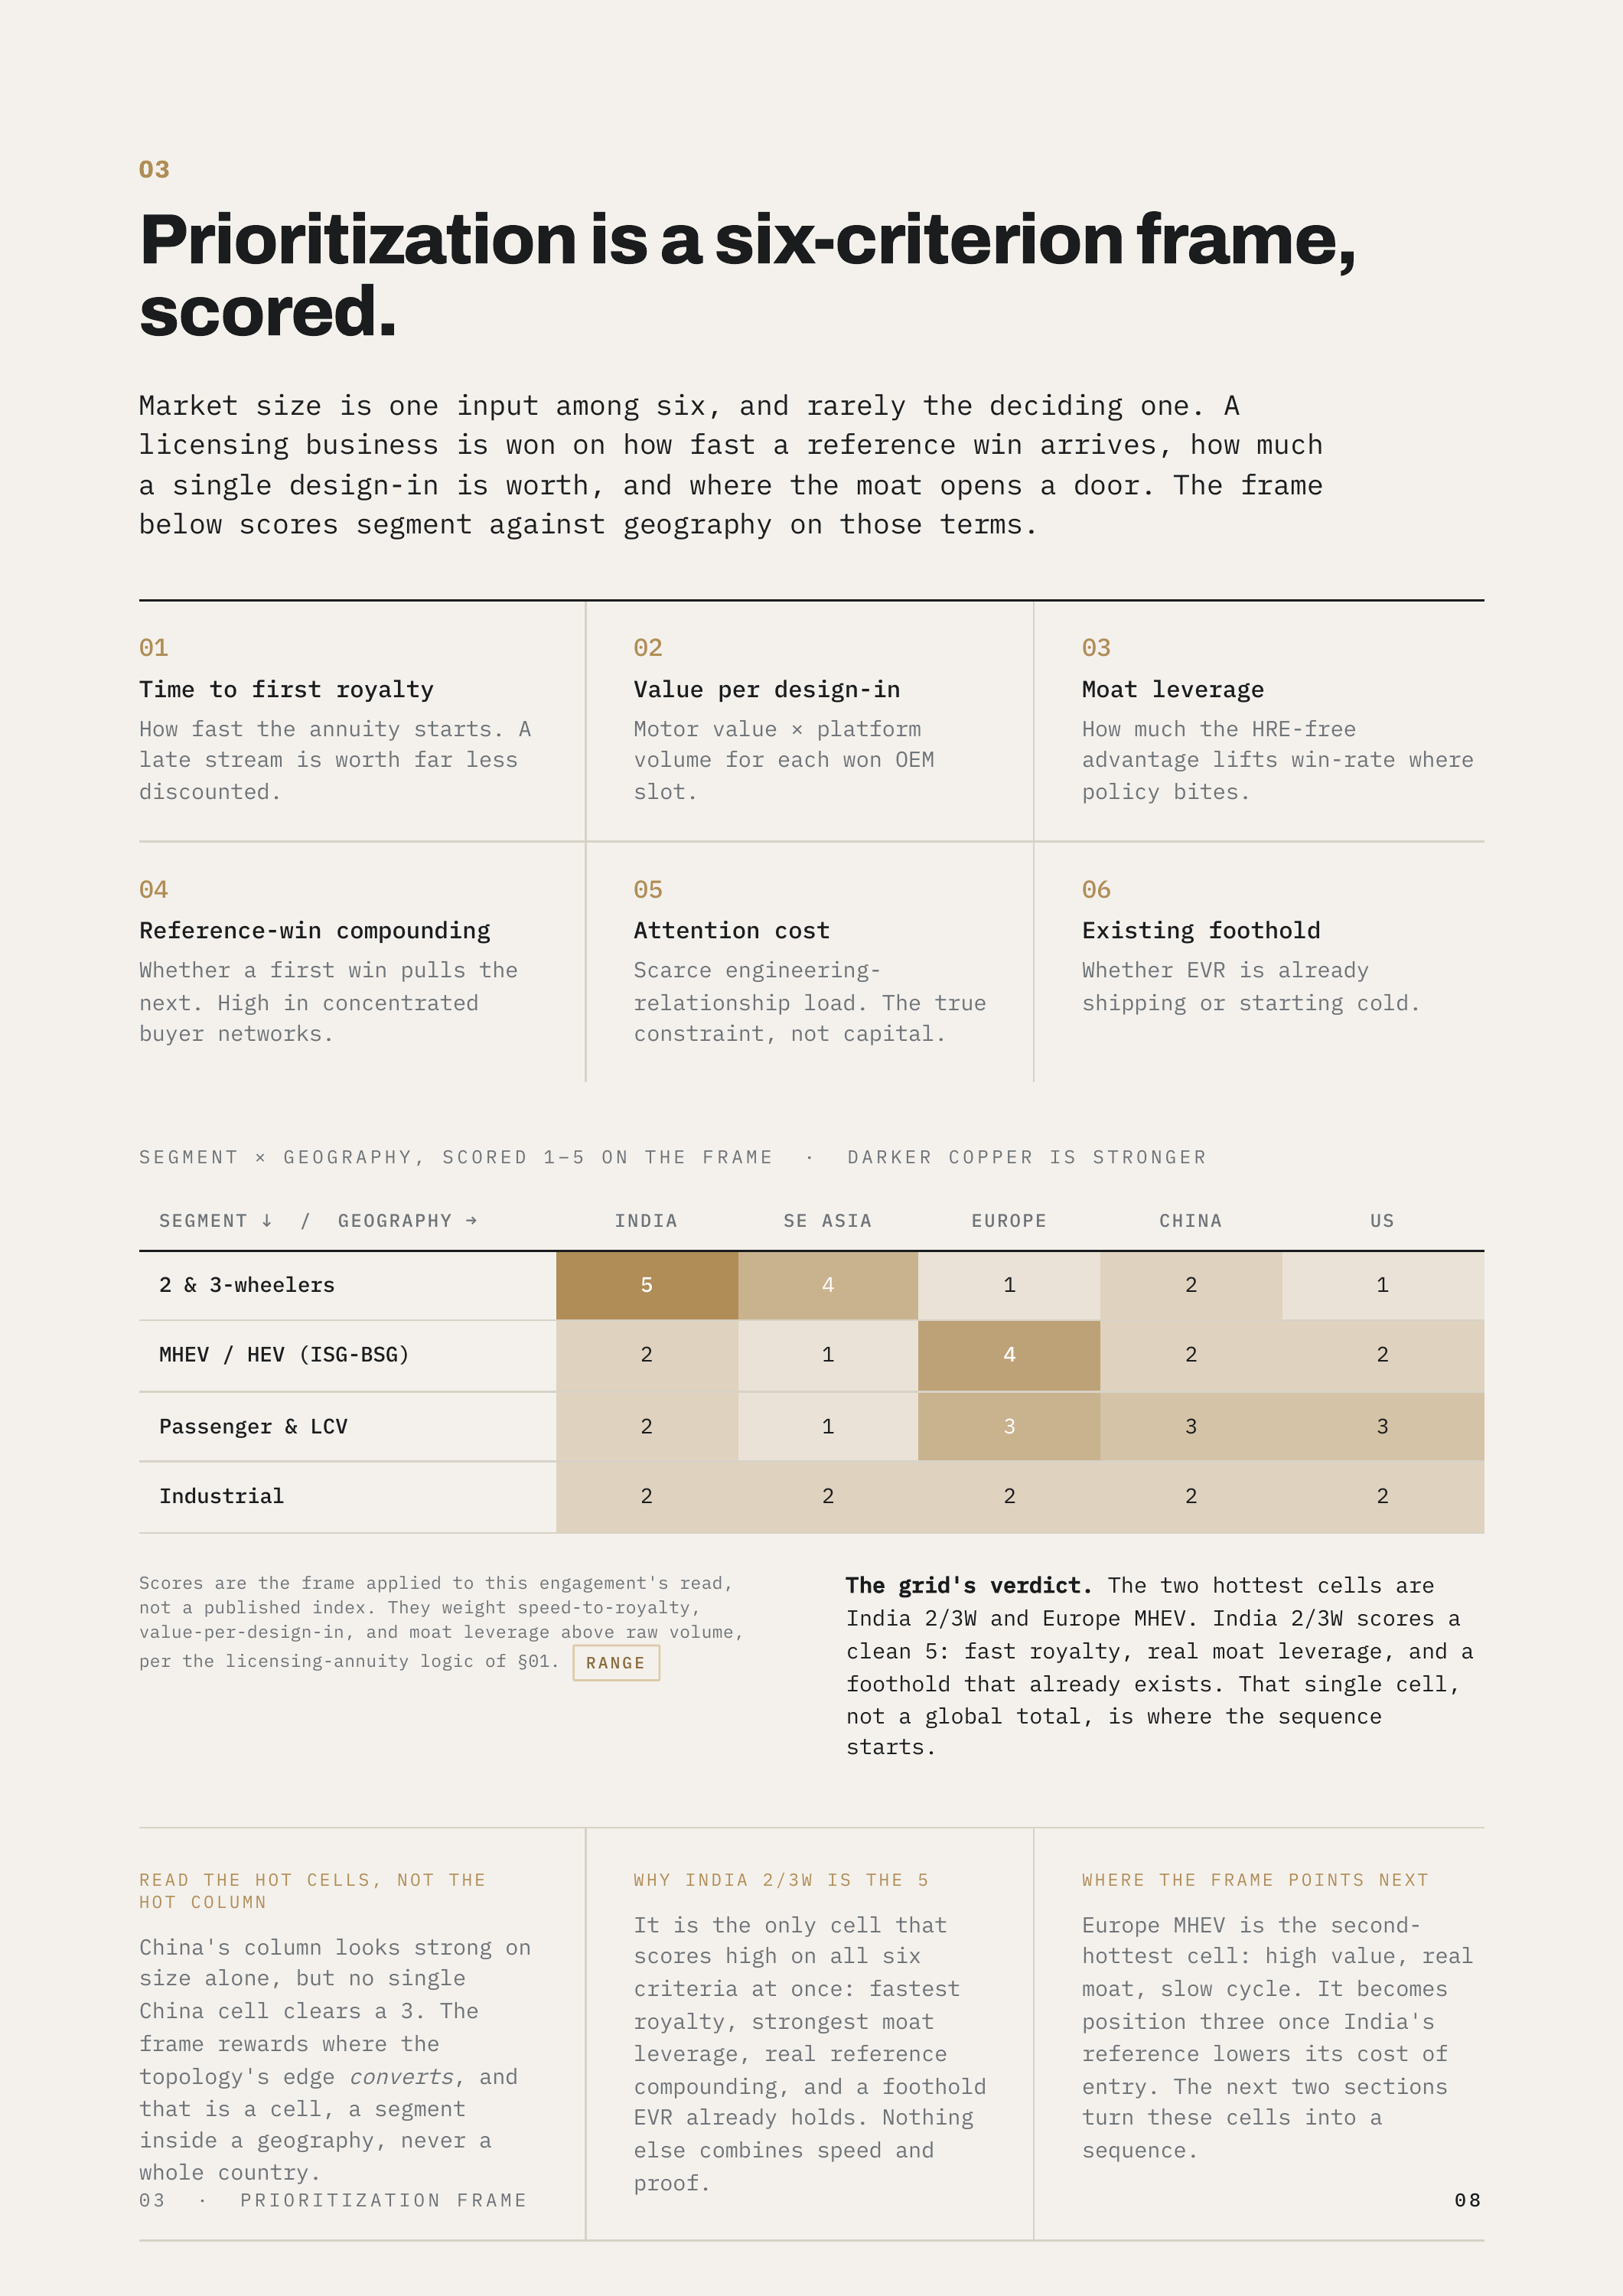
03 Prioritization is a six-criterion frame, scored. Market size is one input among six, and rarely the deciding one. A licensing business is won on how fast a reference win arrives, how much a single design-in is worth, and where the moat opens a door. The frame below scores segment against…
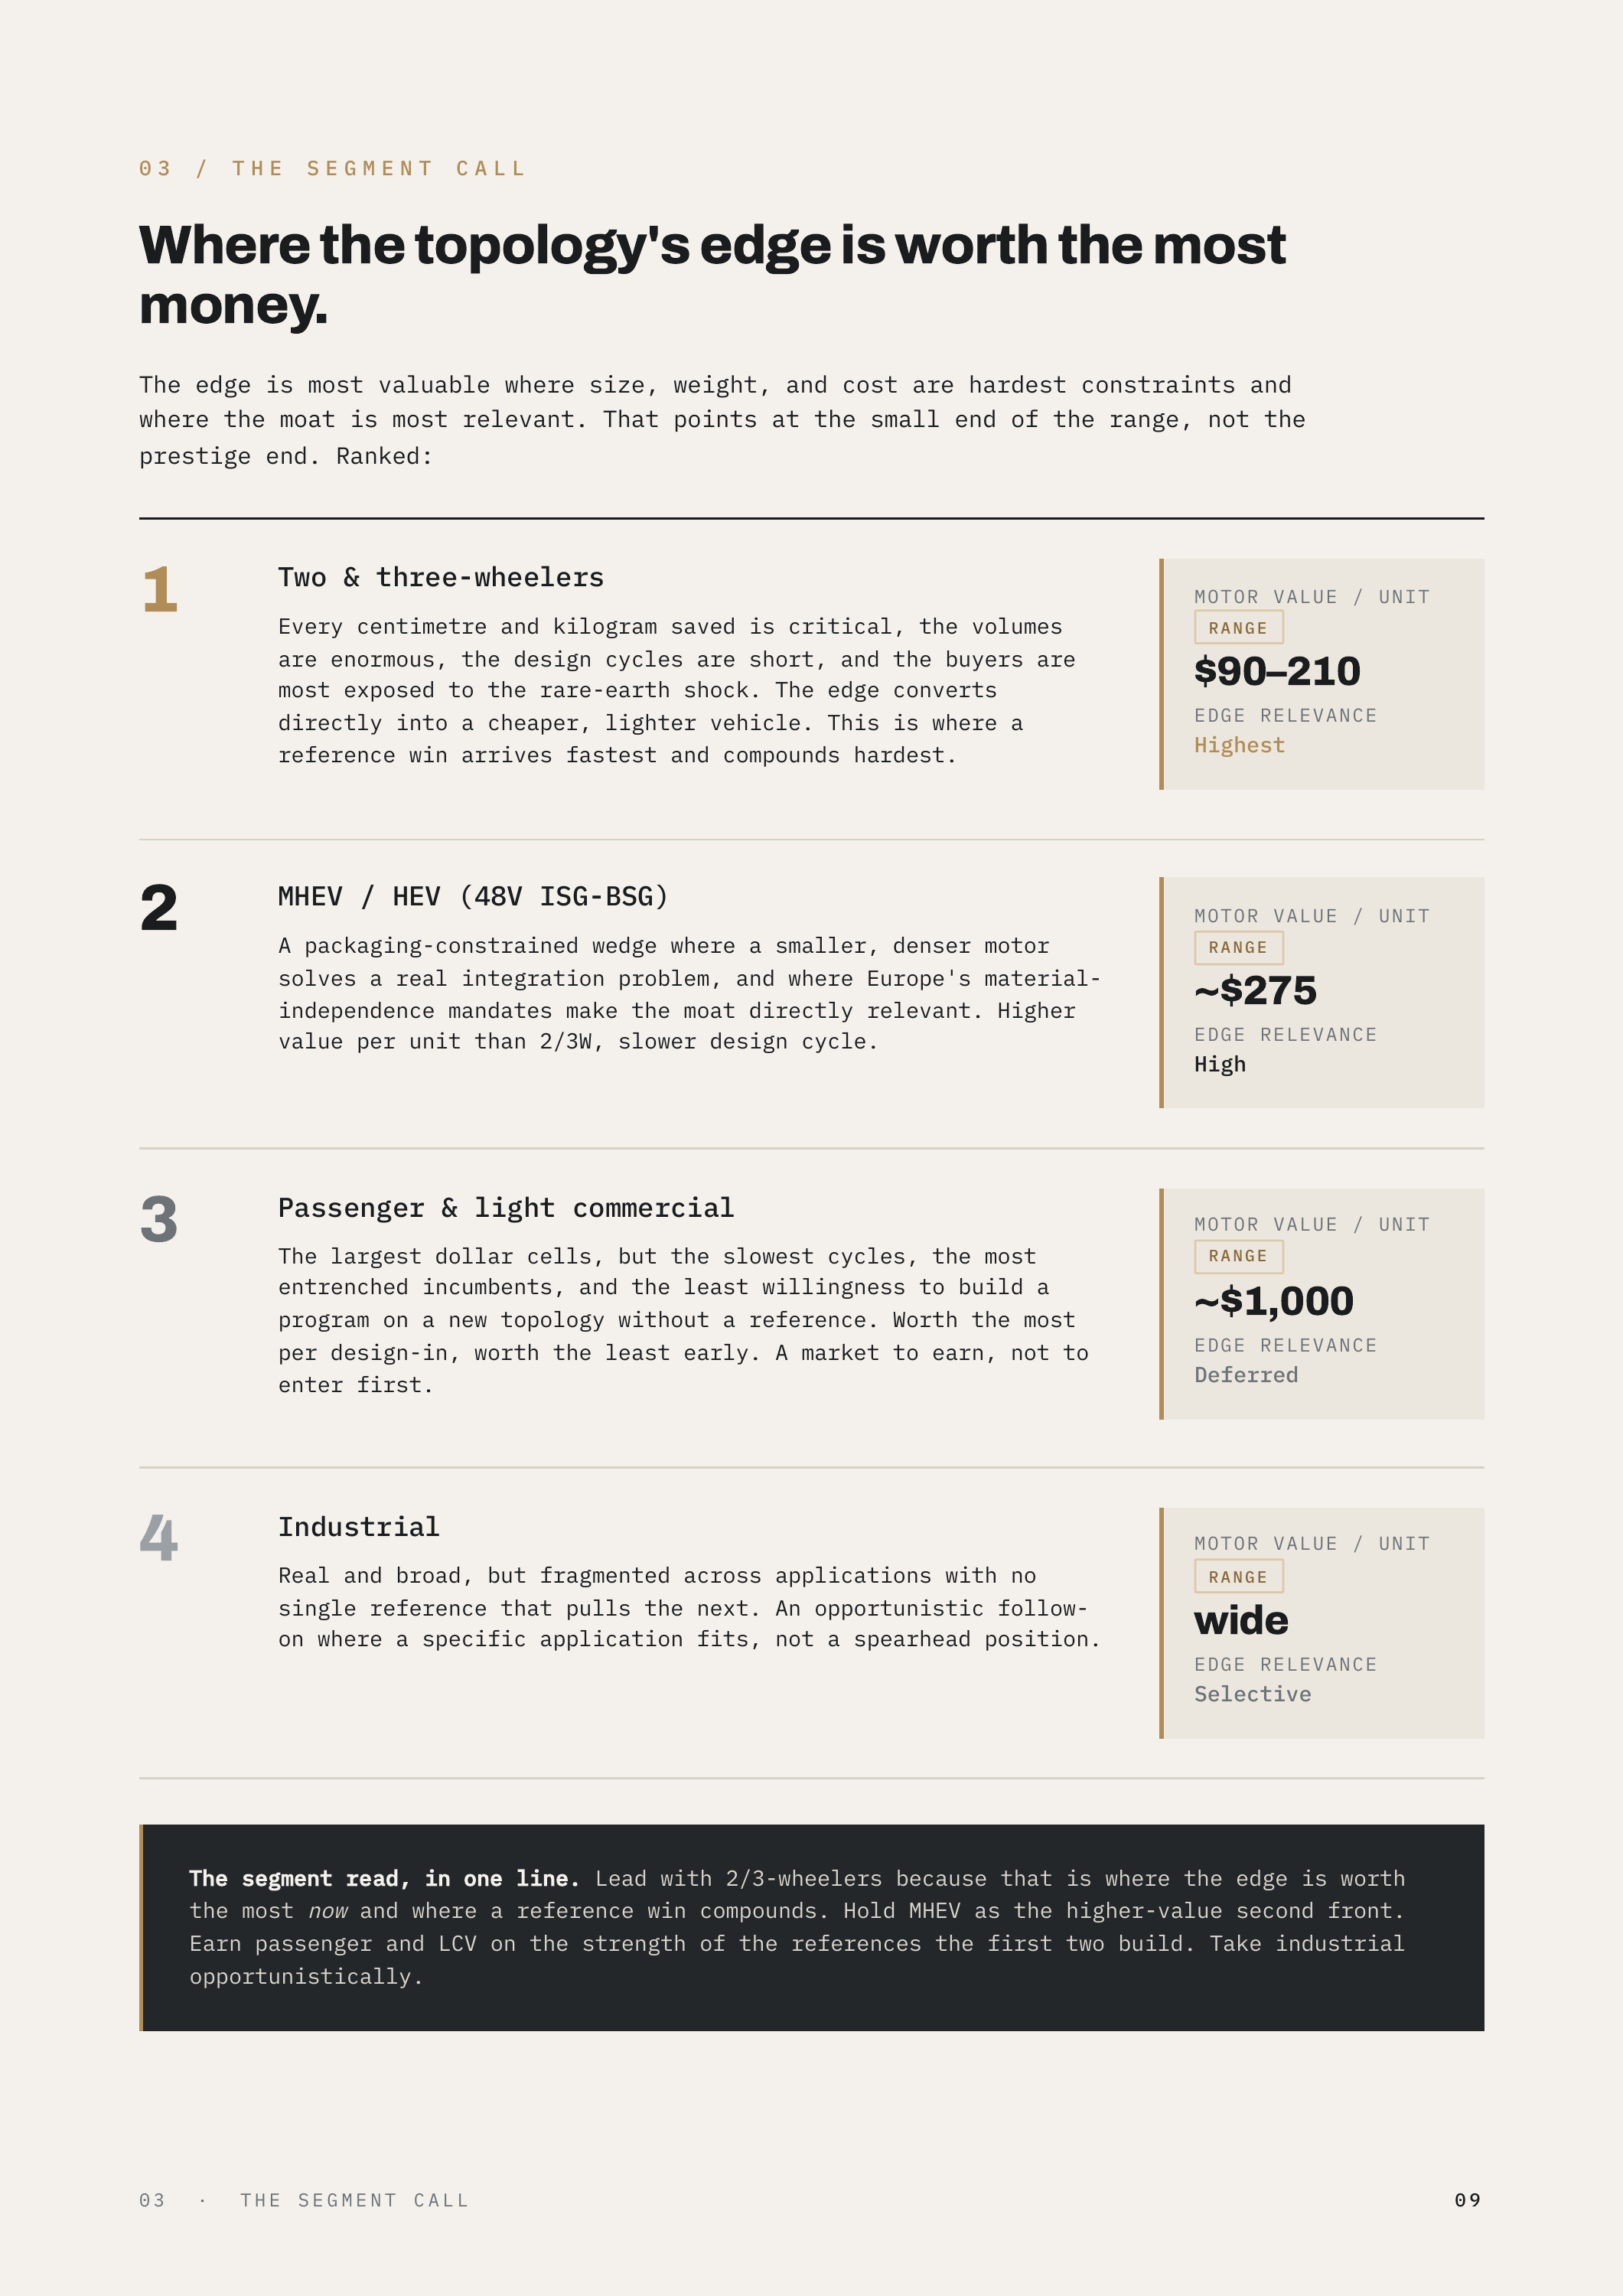
03 / THE SEGMENT CALL Where the topology's edge is worth the most money. The edge is most valuable where size, weight, and cost are hardest constraints and where the moat is most relevant. That points at the small end of the range, not the prestige end. Ranked: 1 Two & three-wheelers Every…
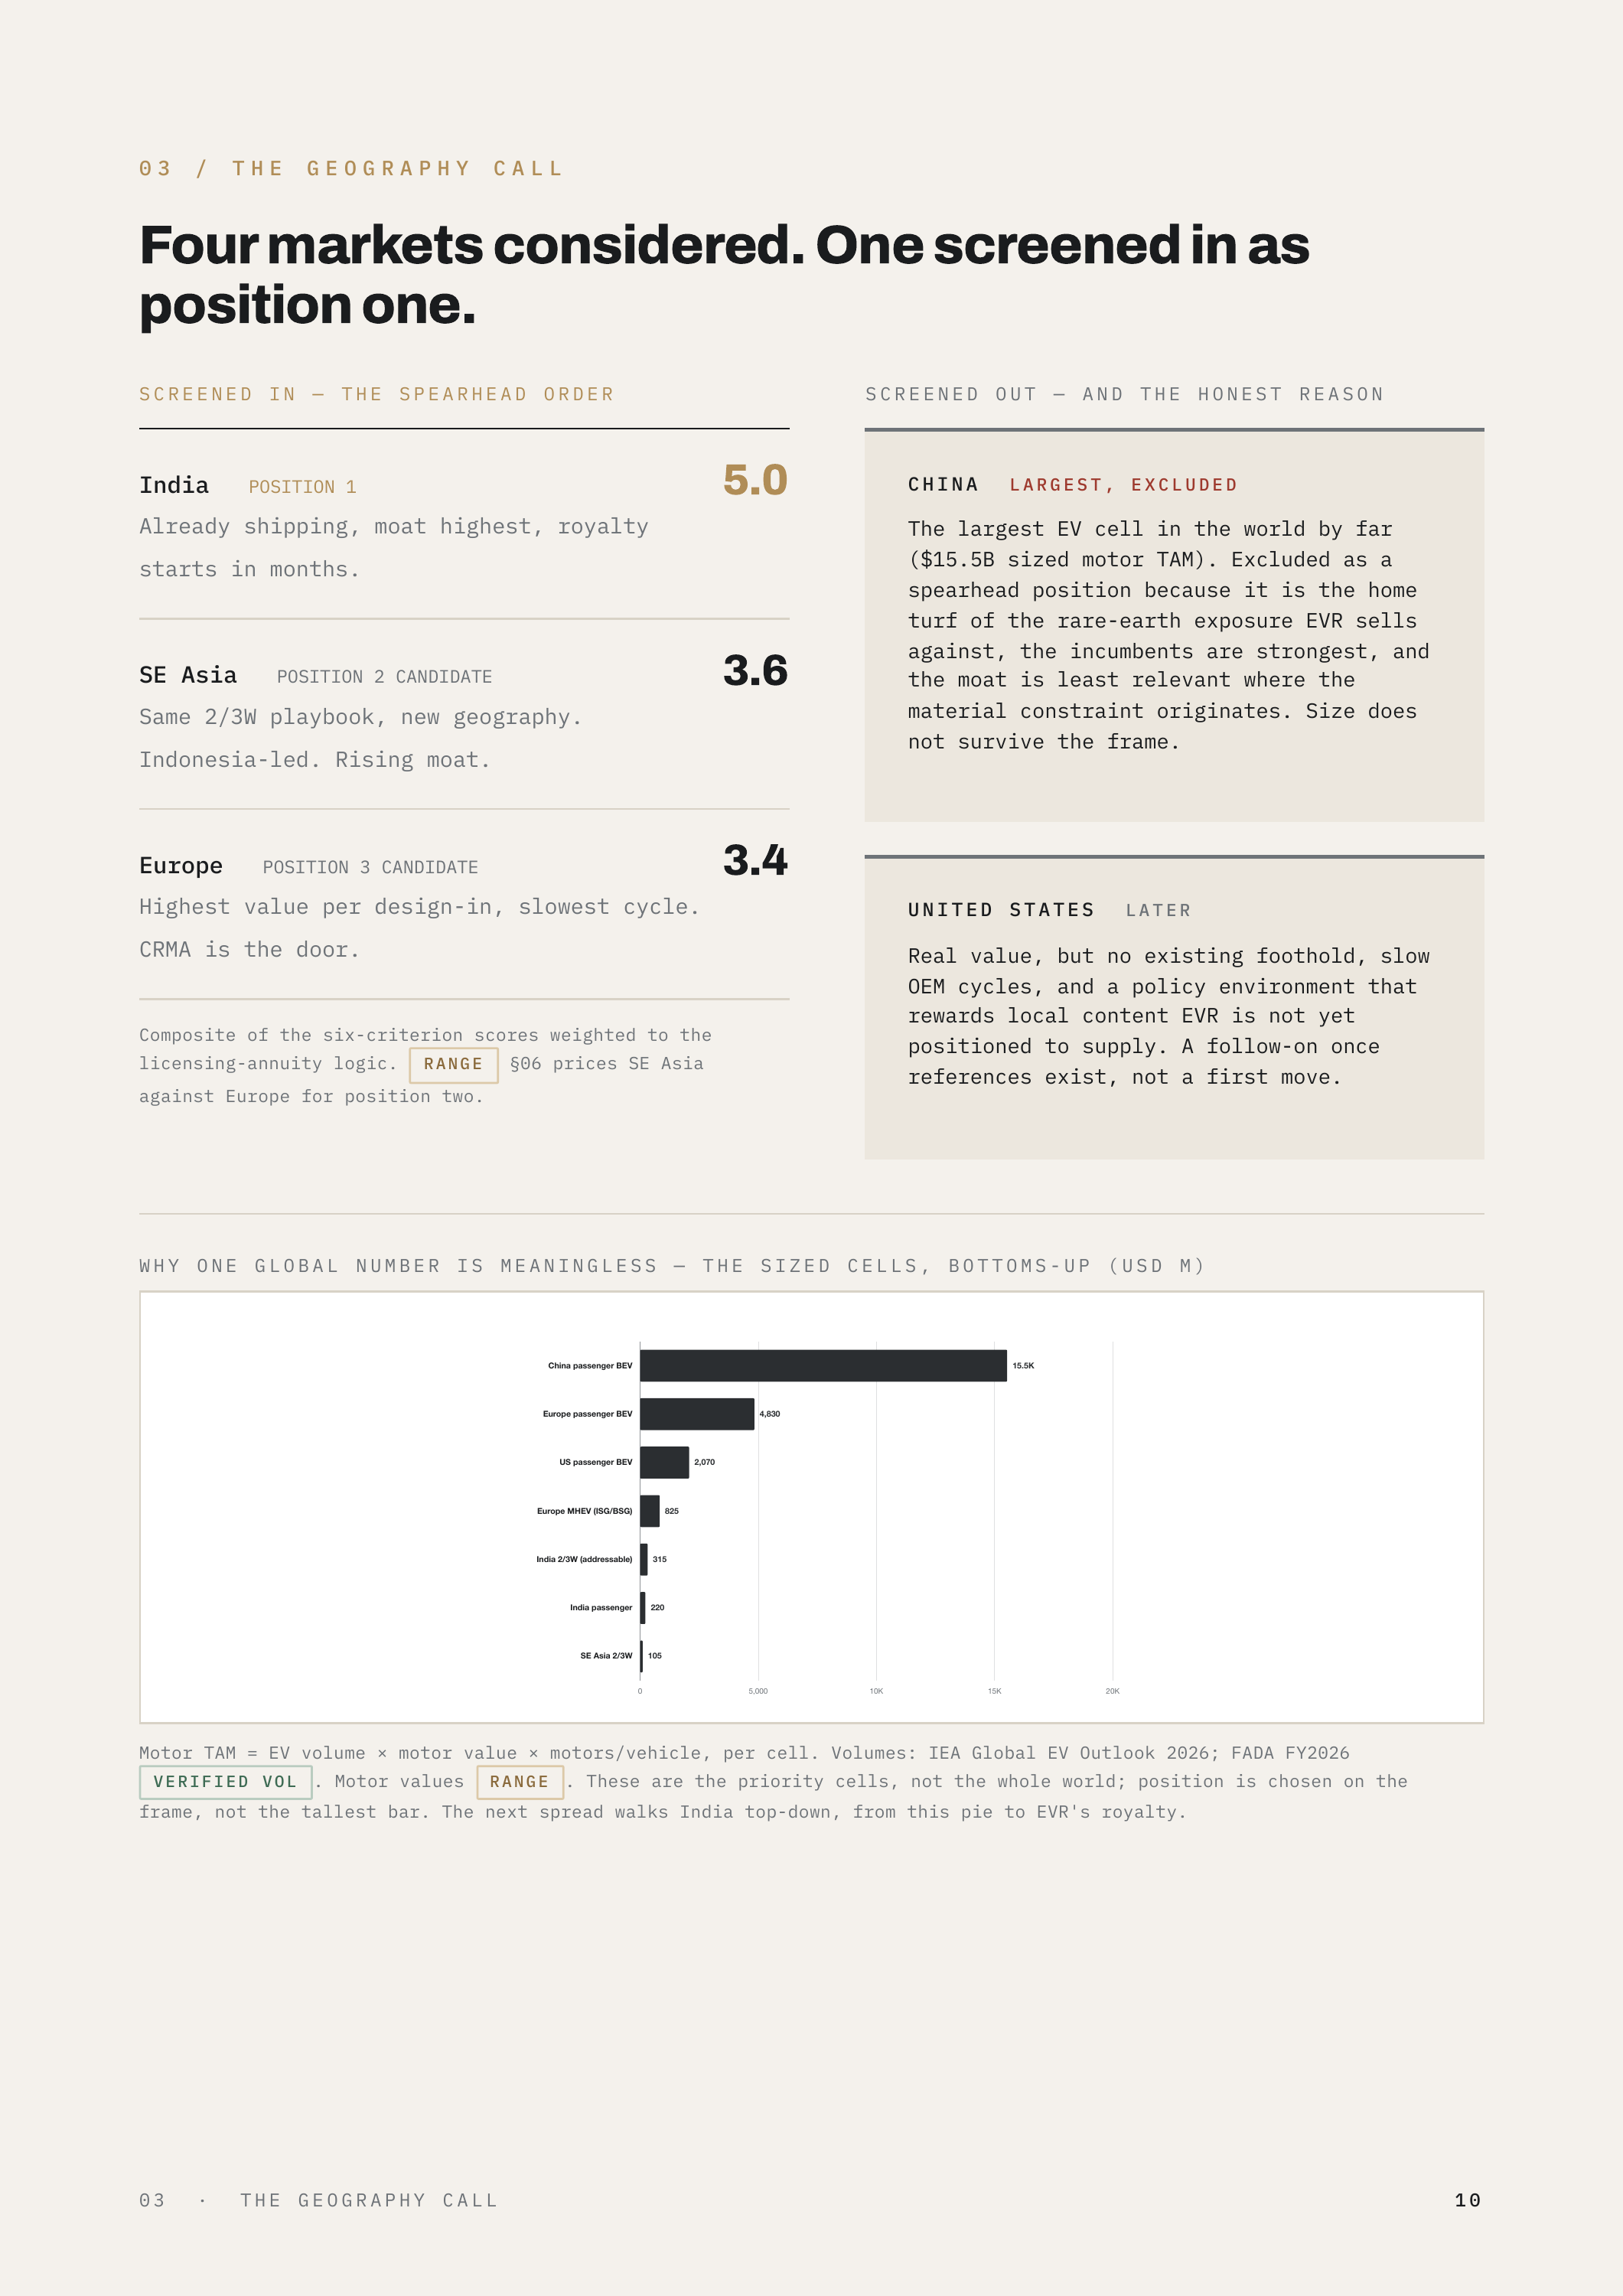
03 / THE GEOGRAPHY CALL Four markets considered. One screened in as position one. SCREENED IN — THE SPEARHEAD ORDER India SCREENED OUT — AND THE HONEST REASON 5.0 POSITION 1 Already shipping, moat highest, royalty CHINA The largest EV cell in the world by far ($15.5B sized motor TAM). Excluded as a…
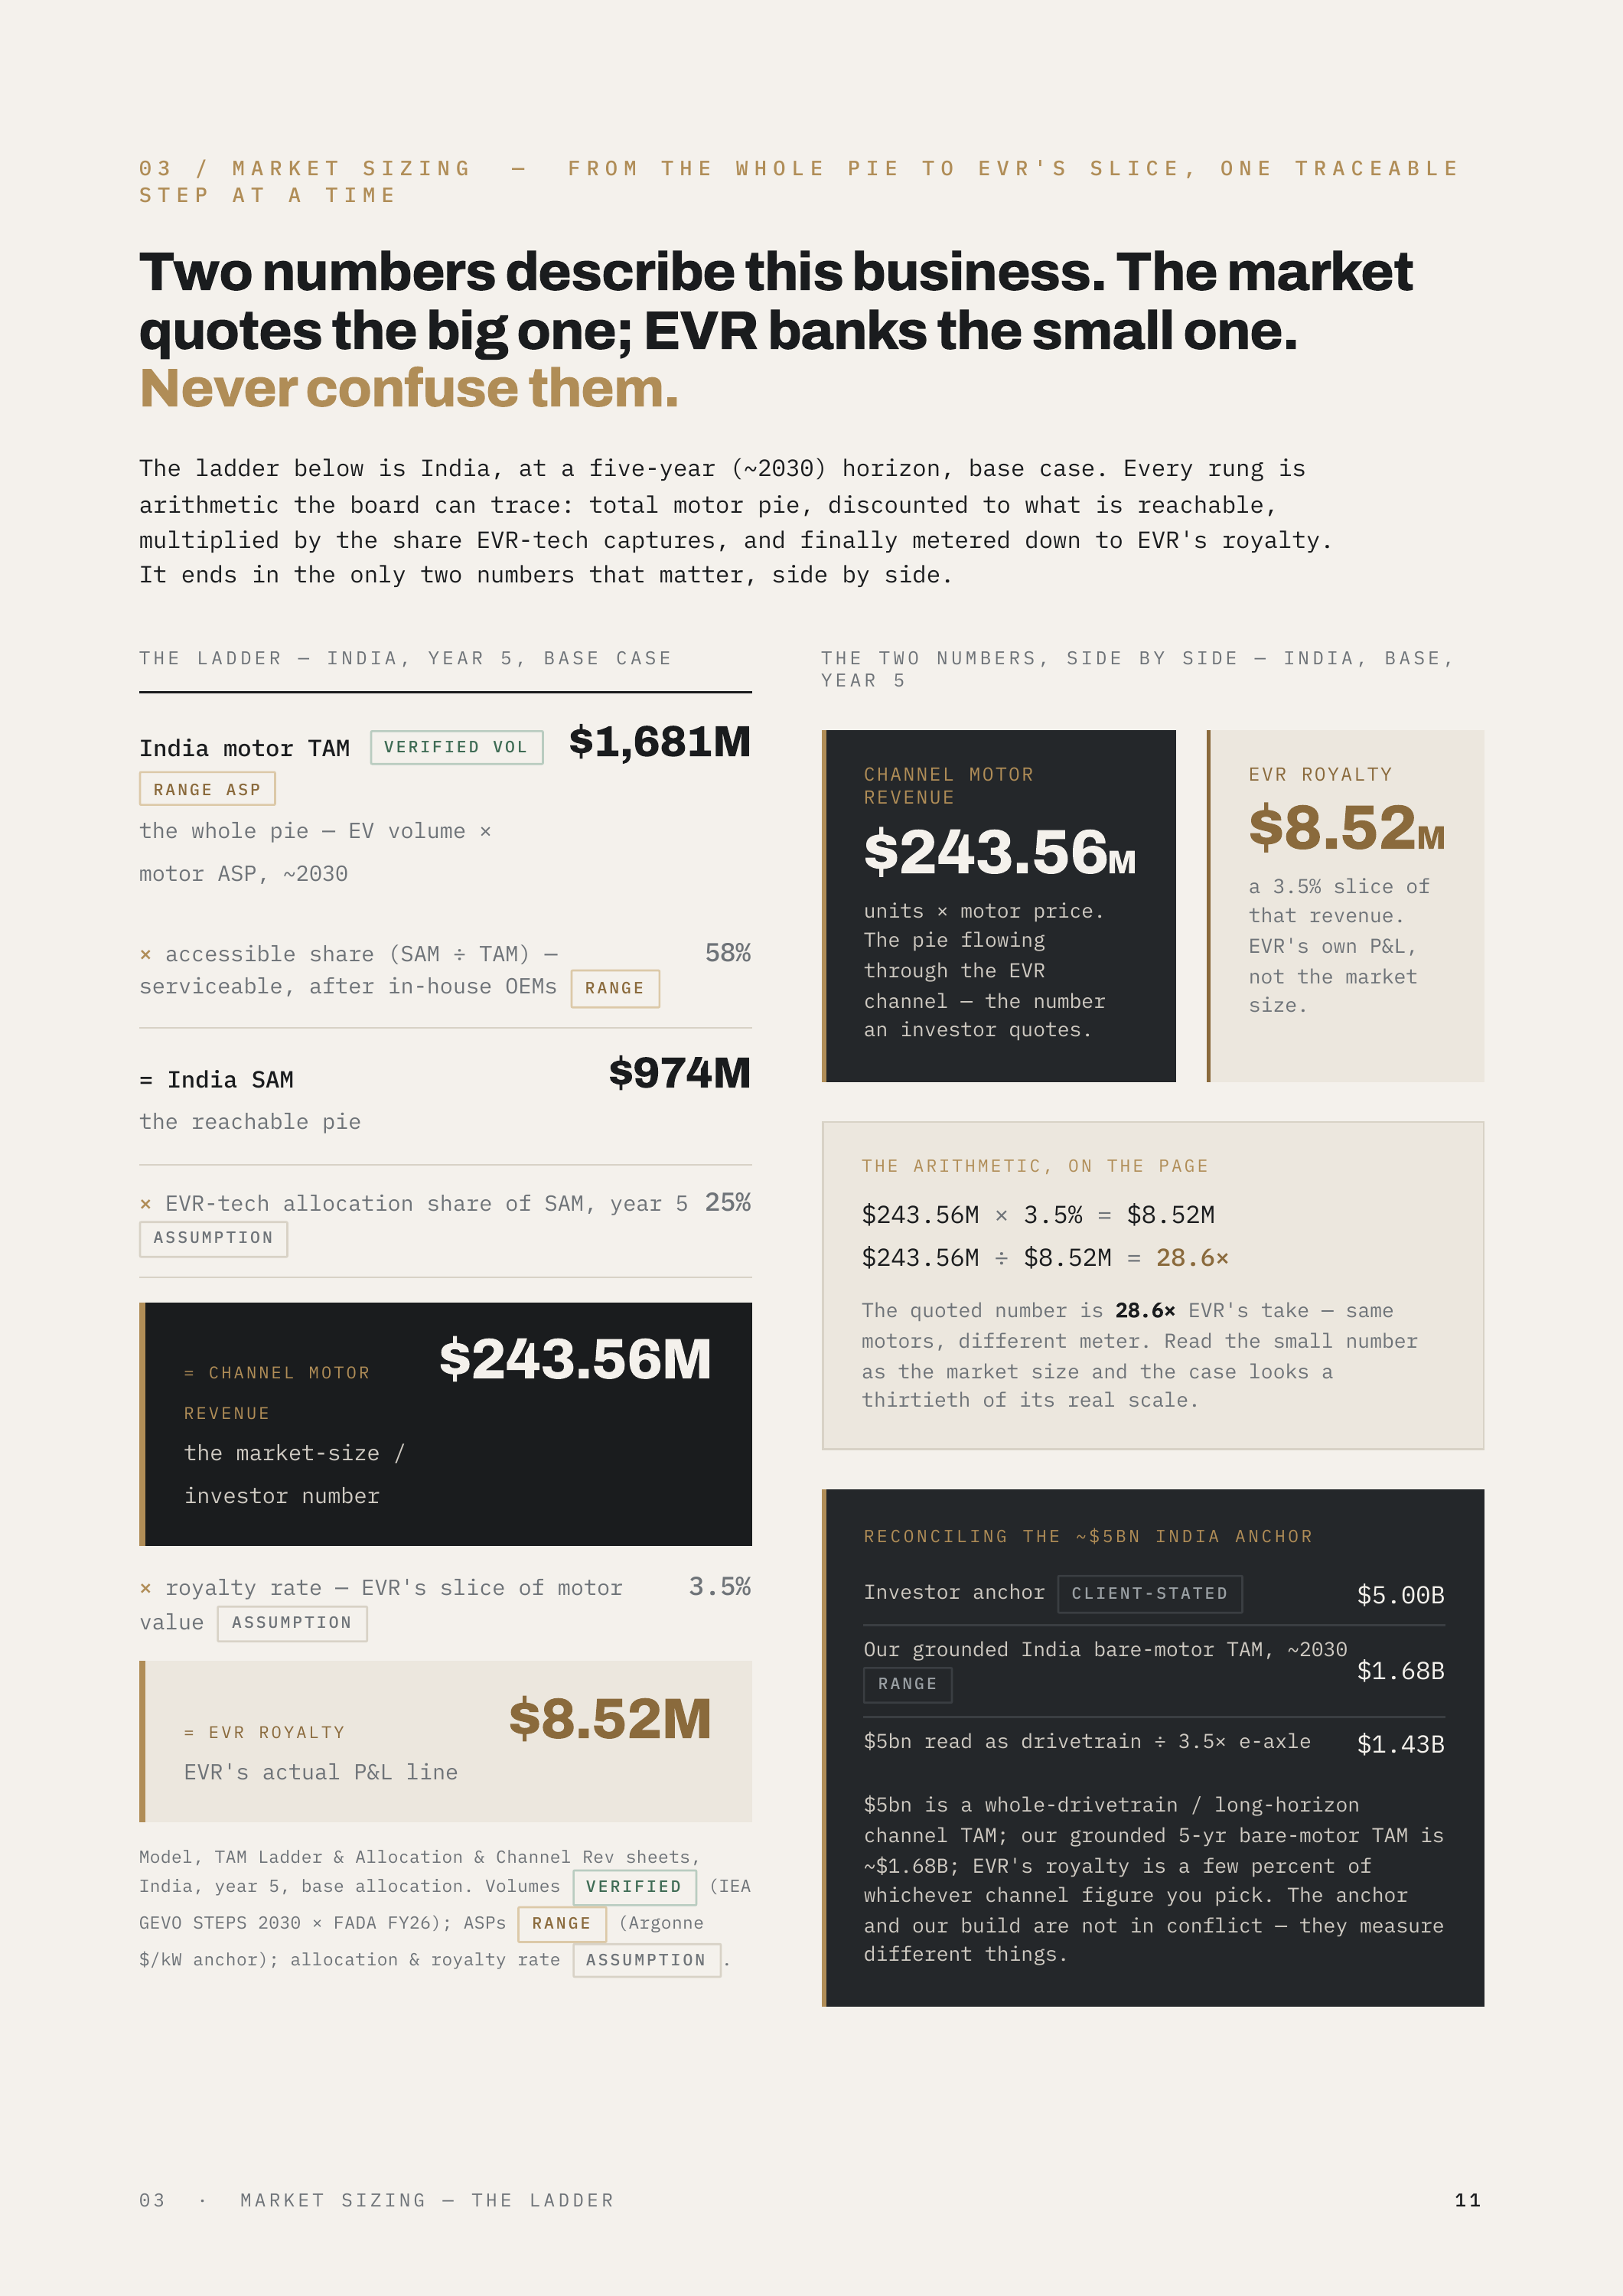
03 / STEP MARKET SIZING AT A TIME — FROM THE WHOLE PIE TO EVR'S SLICE, ONE TRACEABLE Two numbers describe this business. The market quotes the big one; EVR banks the small one. Never confuse them. The ladder below is India, at a five-year (~2030) horizon, base case. Every rung is arithmetic the…
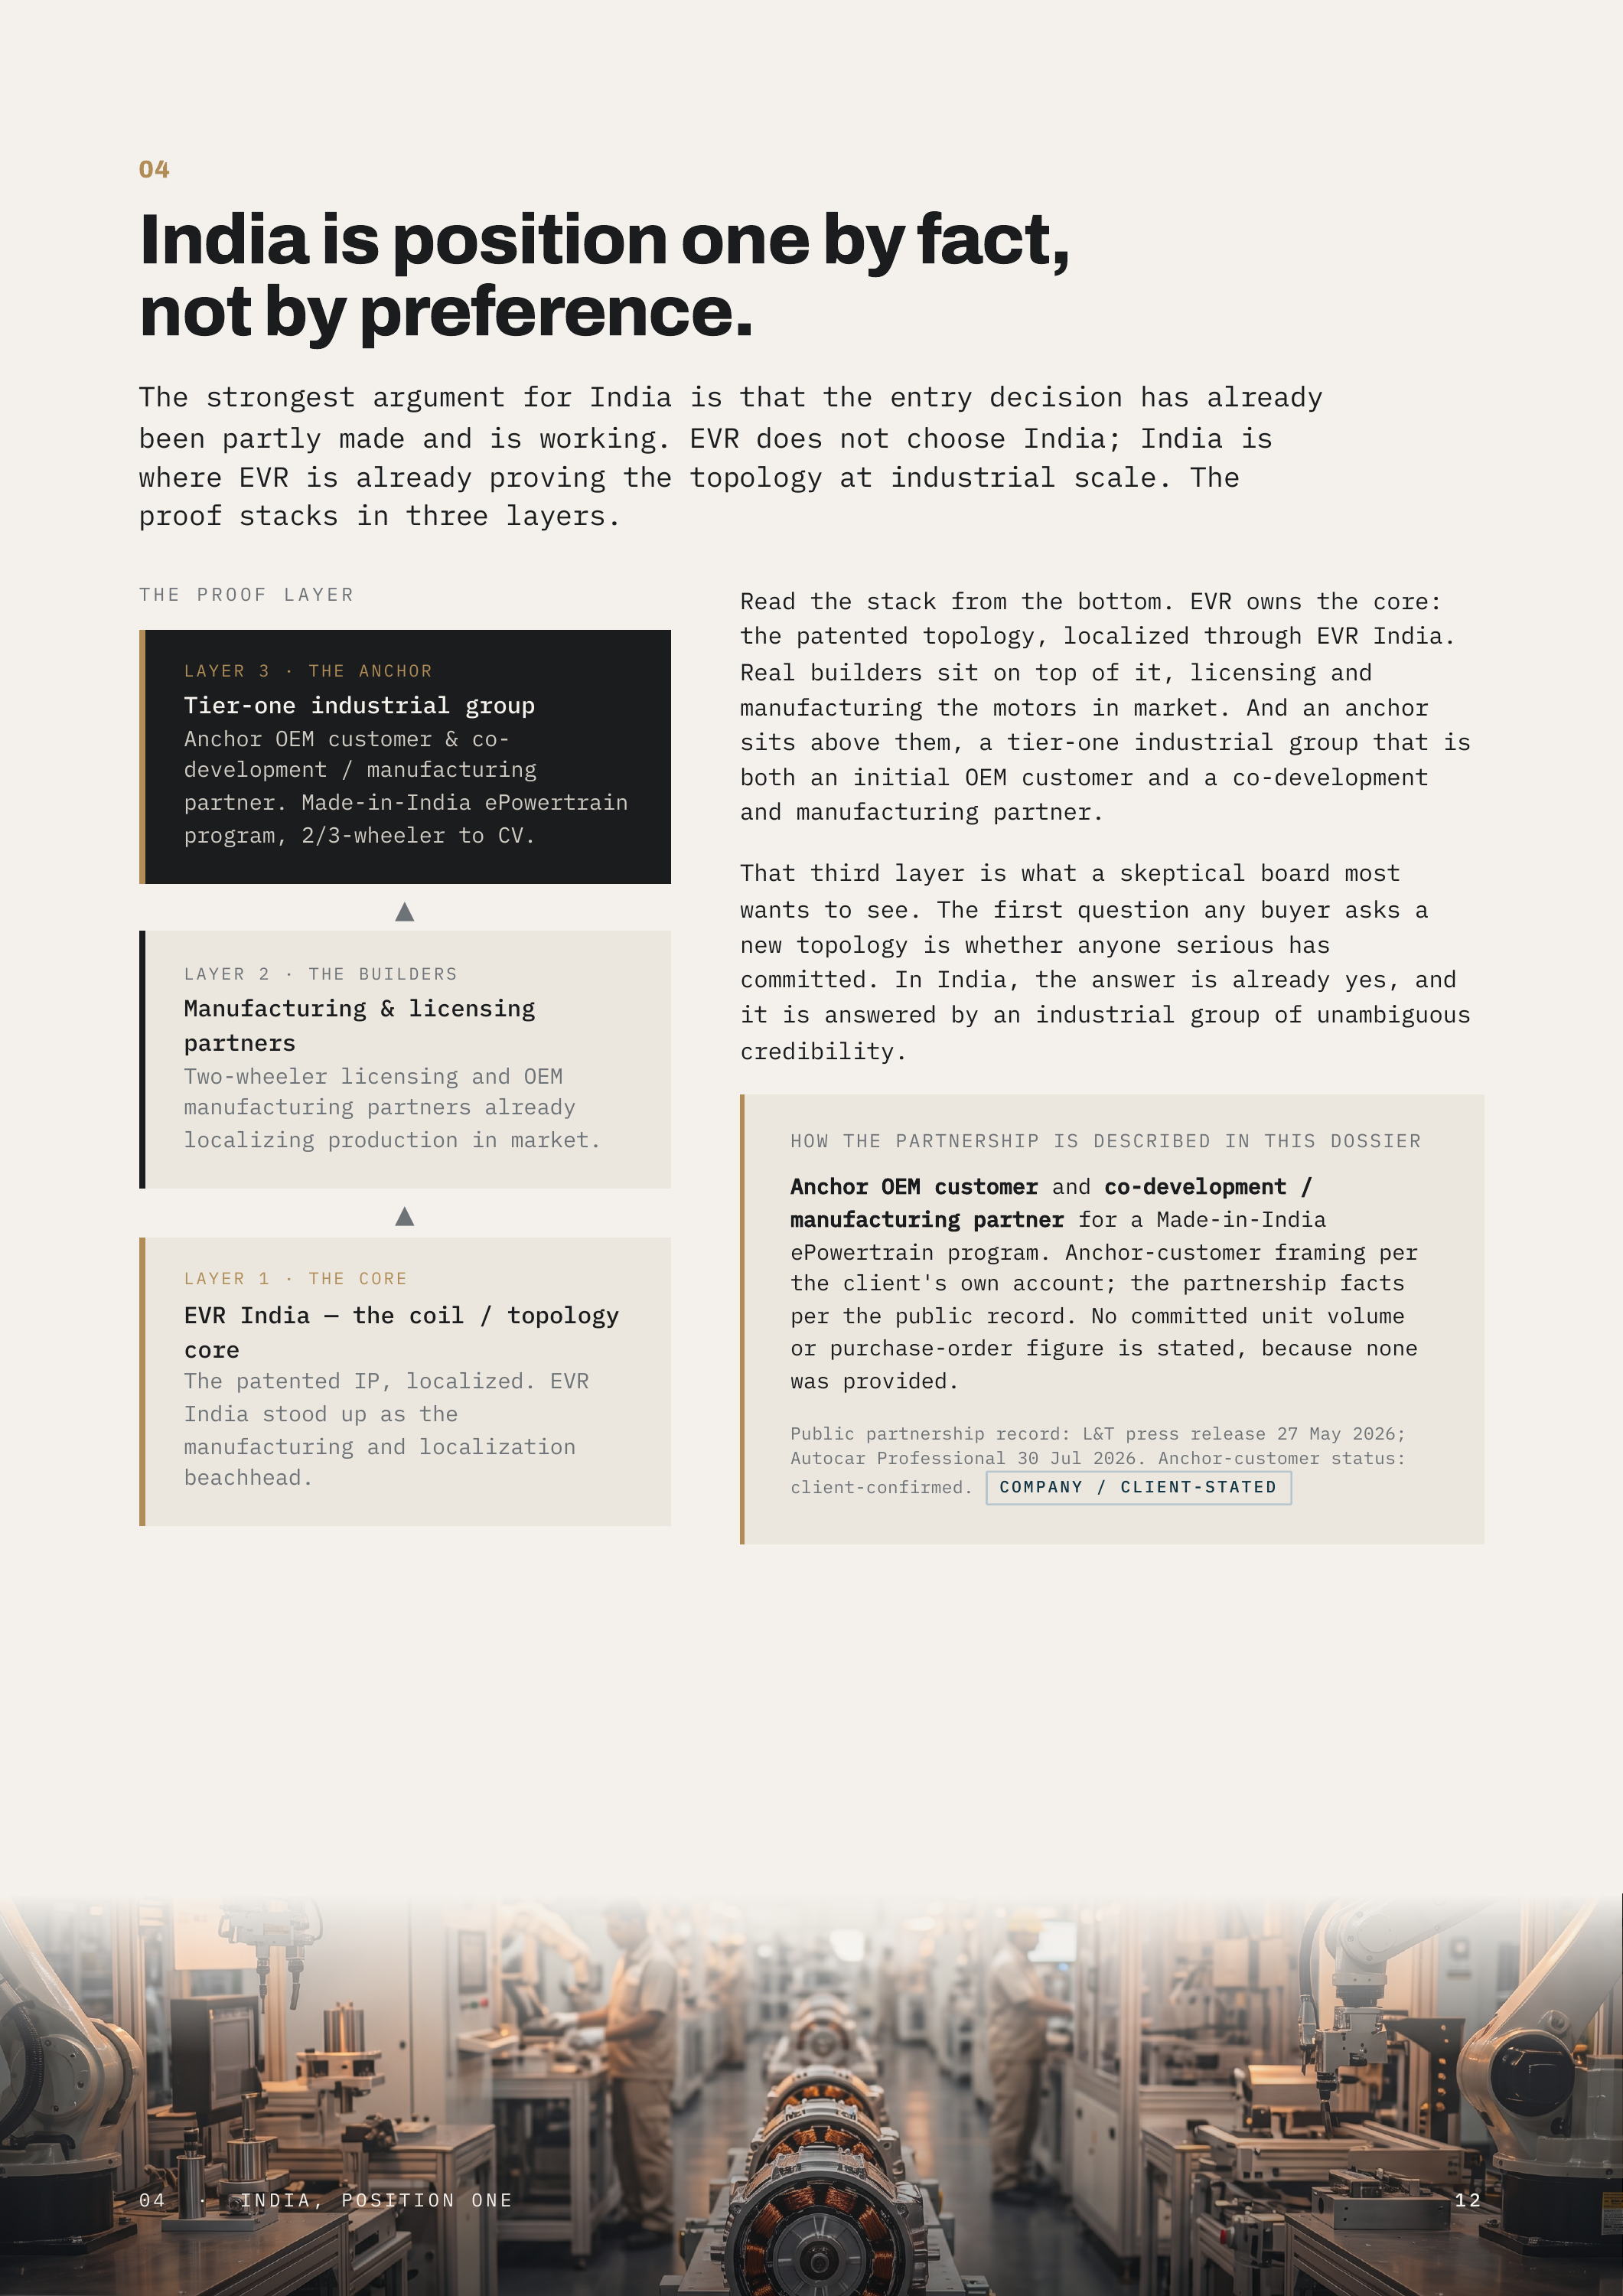
04 India is position one by fact, not by preference. The strongest argument for India is that the entry decision has already been partly made and is working. EVR does not choose India; India is where EVR is already proving the topology at industrial scale. The proof stacks in three layers. THE…
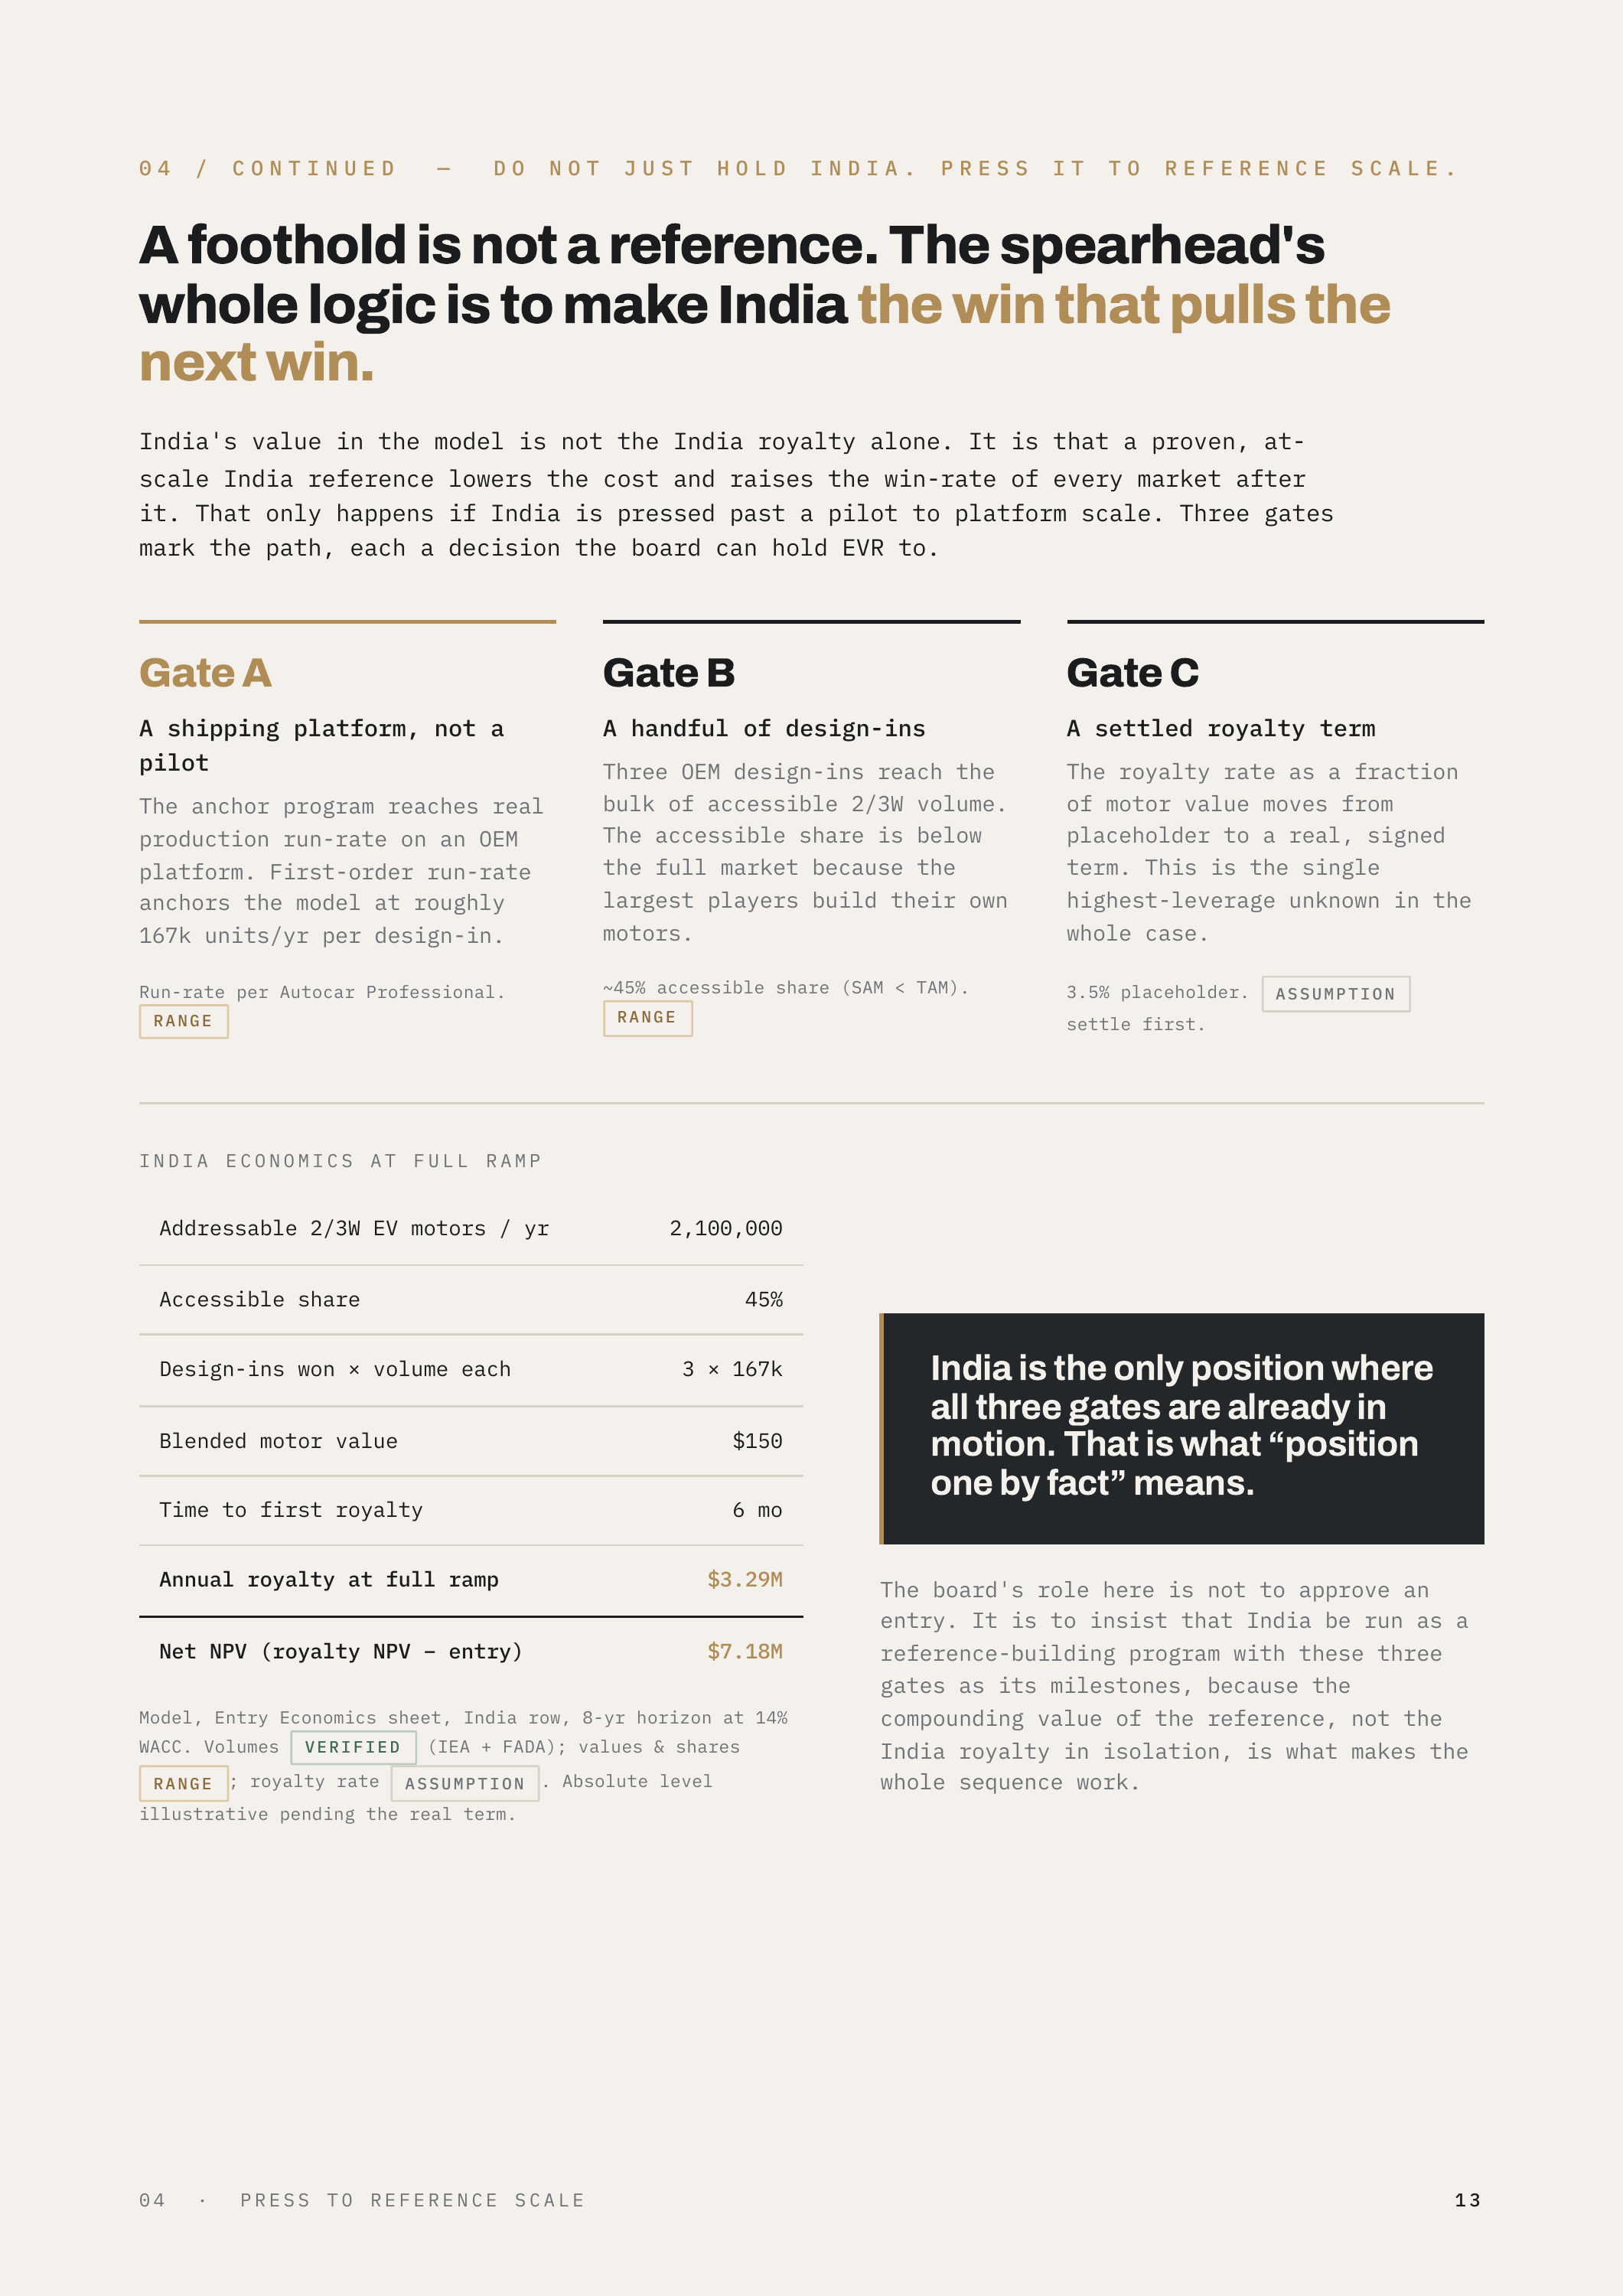
04 / CONTINUED — DO NOT JUST HOLD INDIA. PRESS IT TO REFERENCE SCALE. A foothold is not a reference. The spearhead's whole logic is to make India the win that pulls the next win. India's value in the model is not the India royalty alone. It is that a proven, atscale India reference lowers the cost…
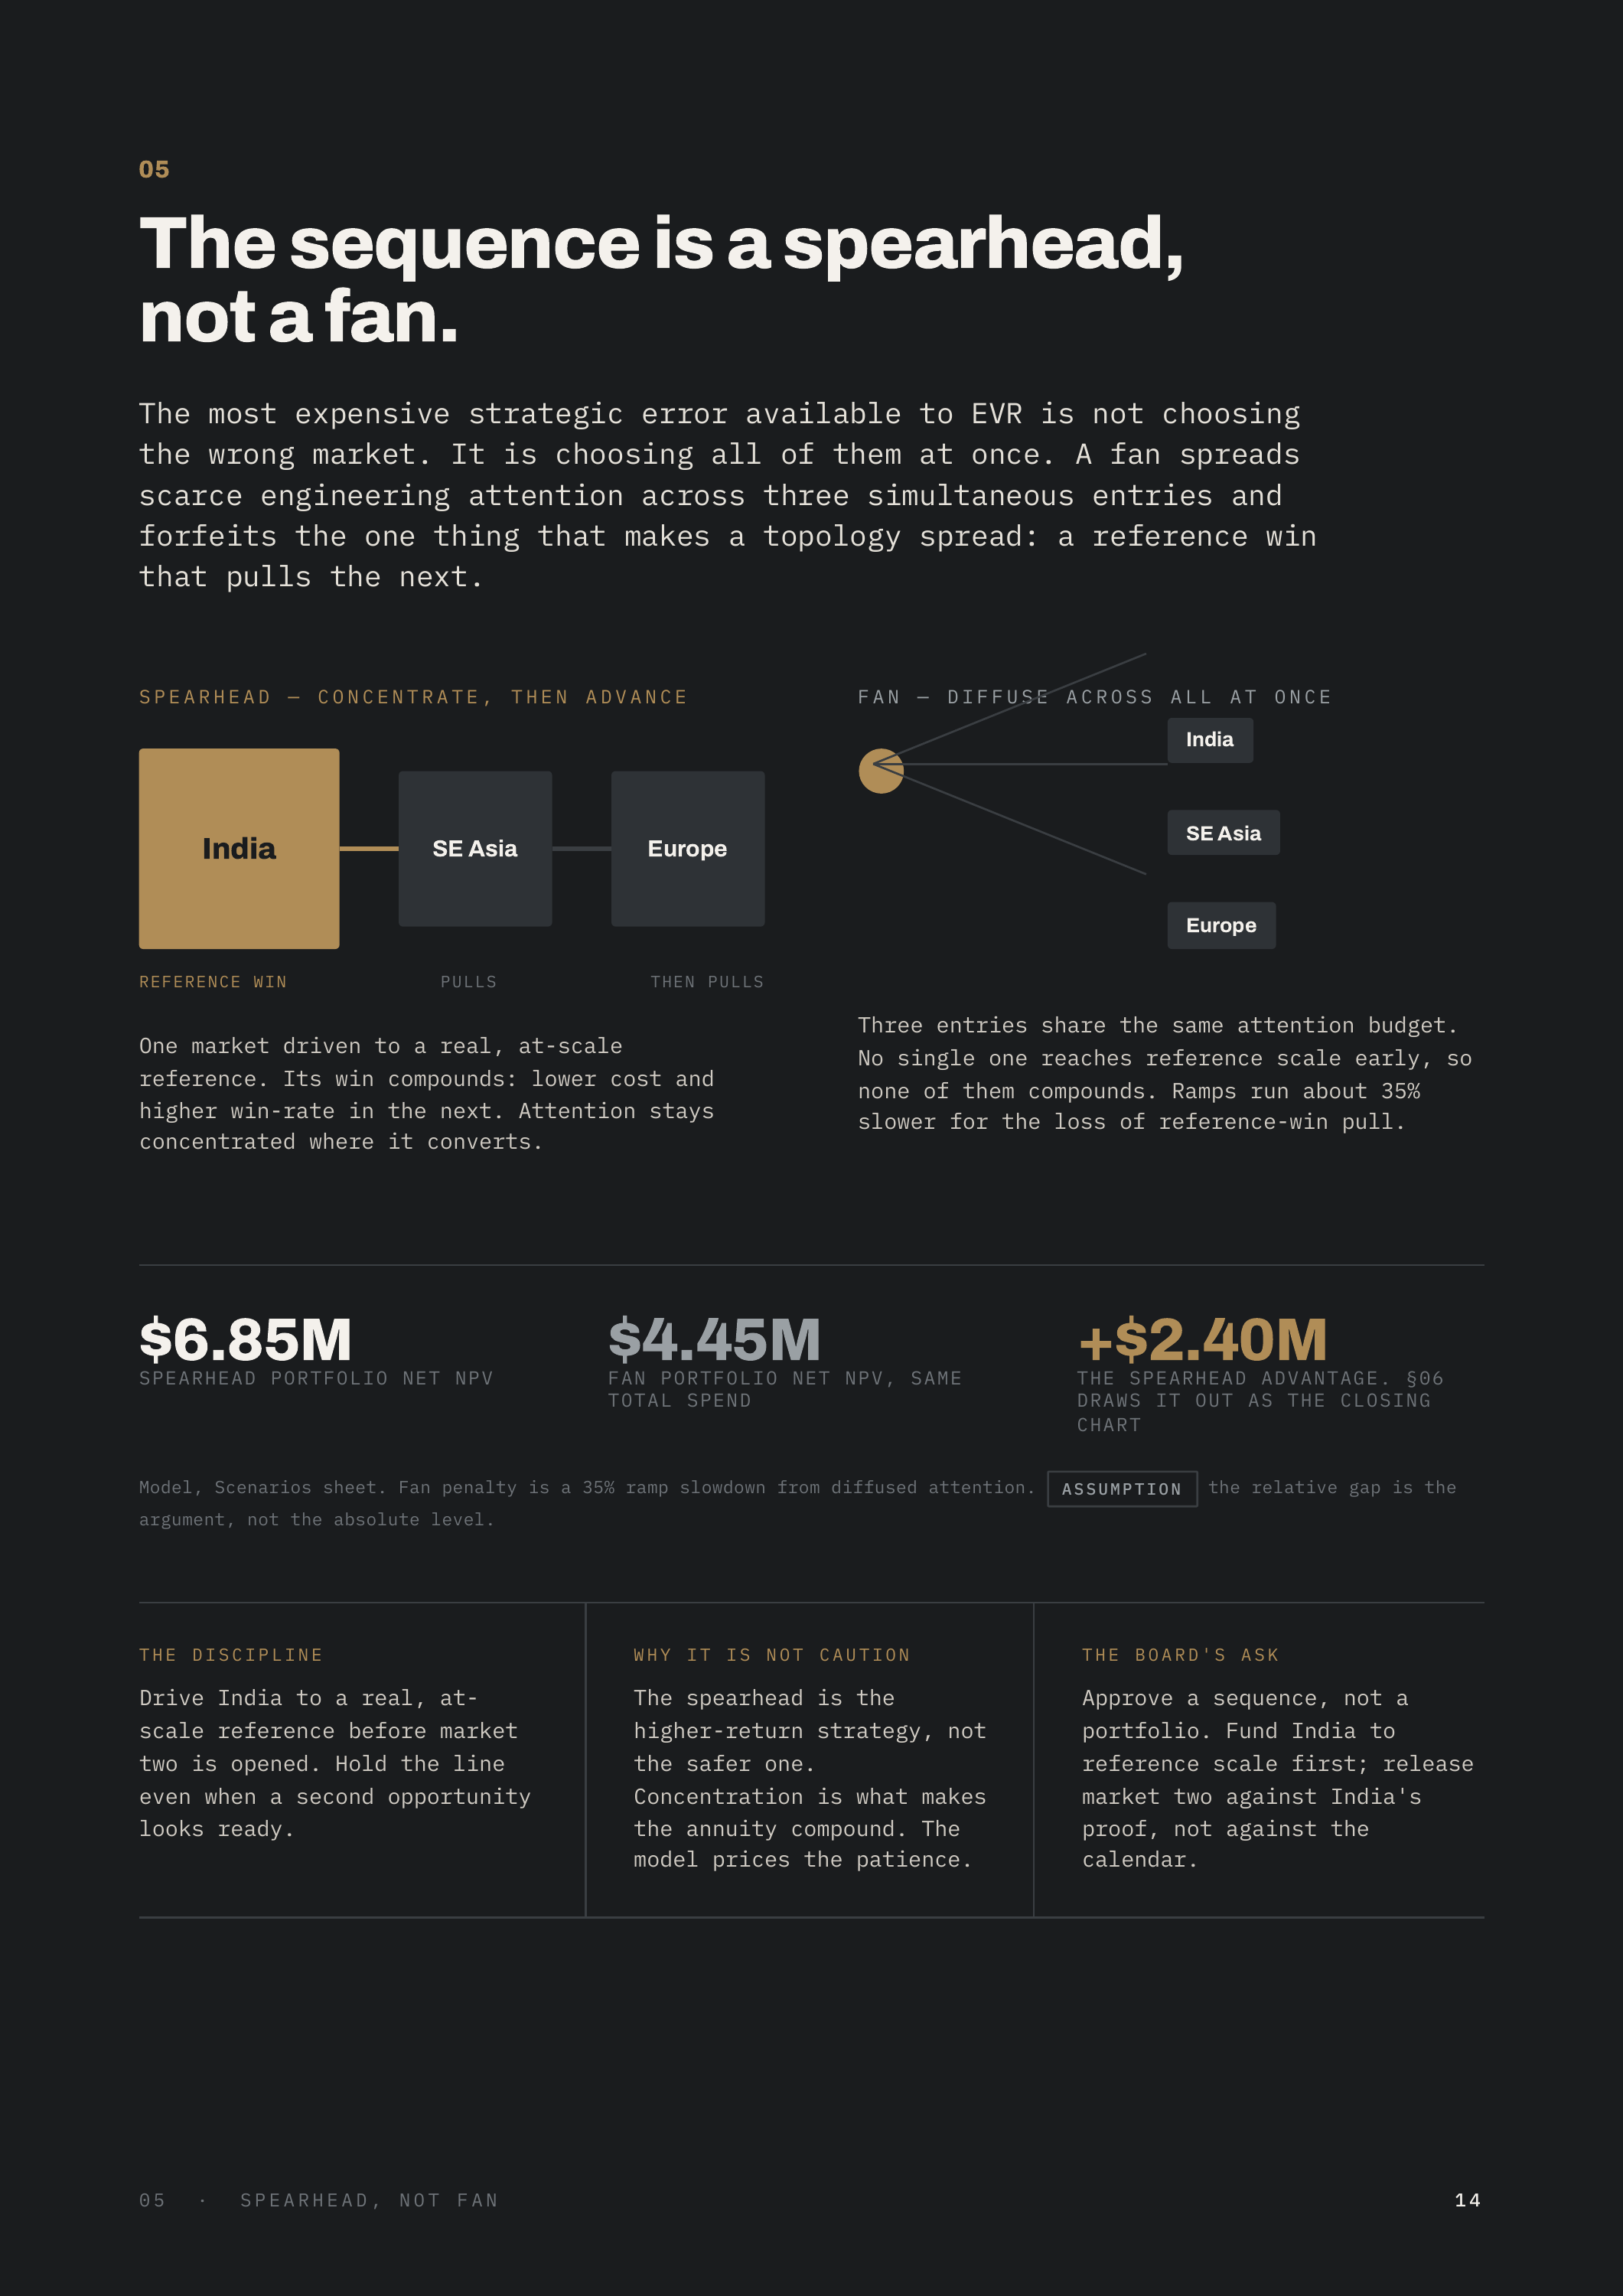
05 The sequence is a spearhead, not a fan. The most expensive strategic error available to EVR is not choosing the wrong market. It is choosing all of them at once. A fan spreads scarce engineering attention across three simultaneous entries and forfeits the one thing that makes a topology spread:…
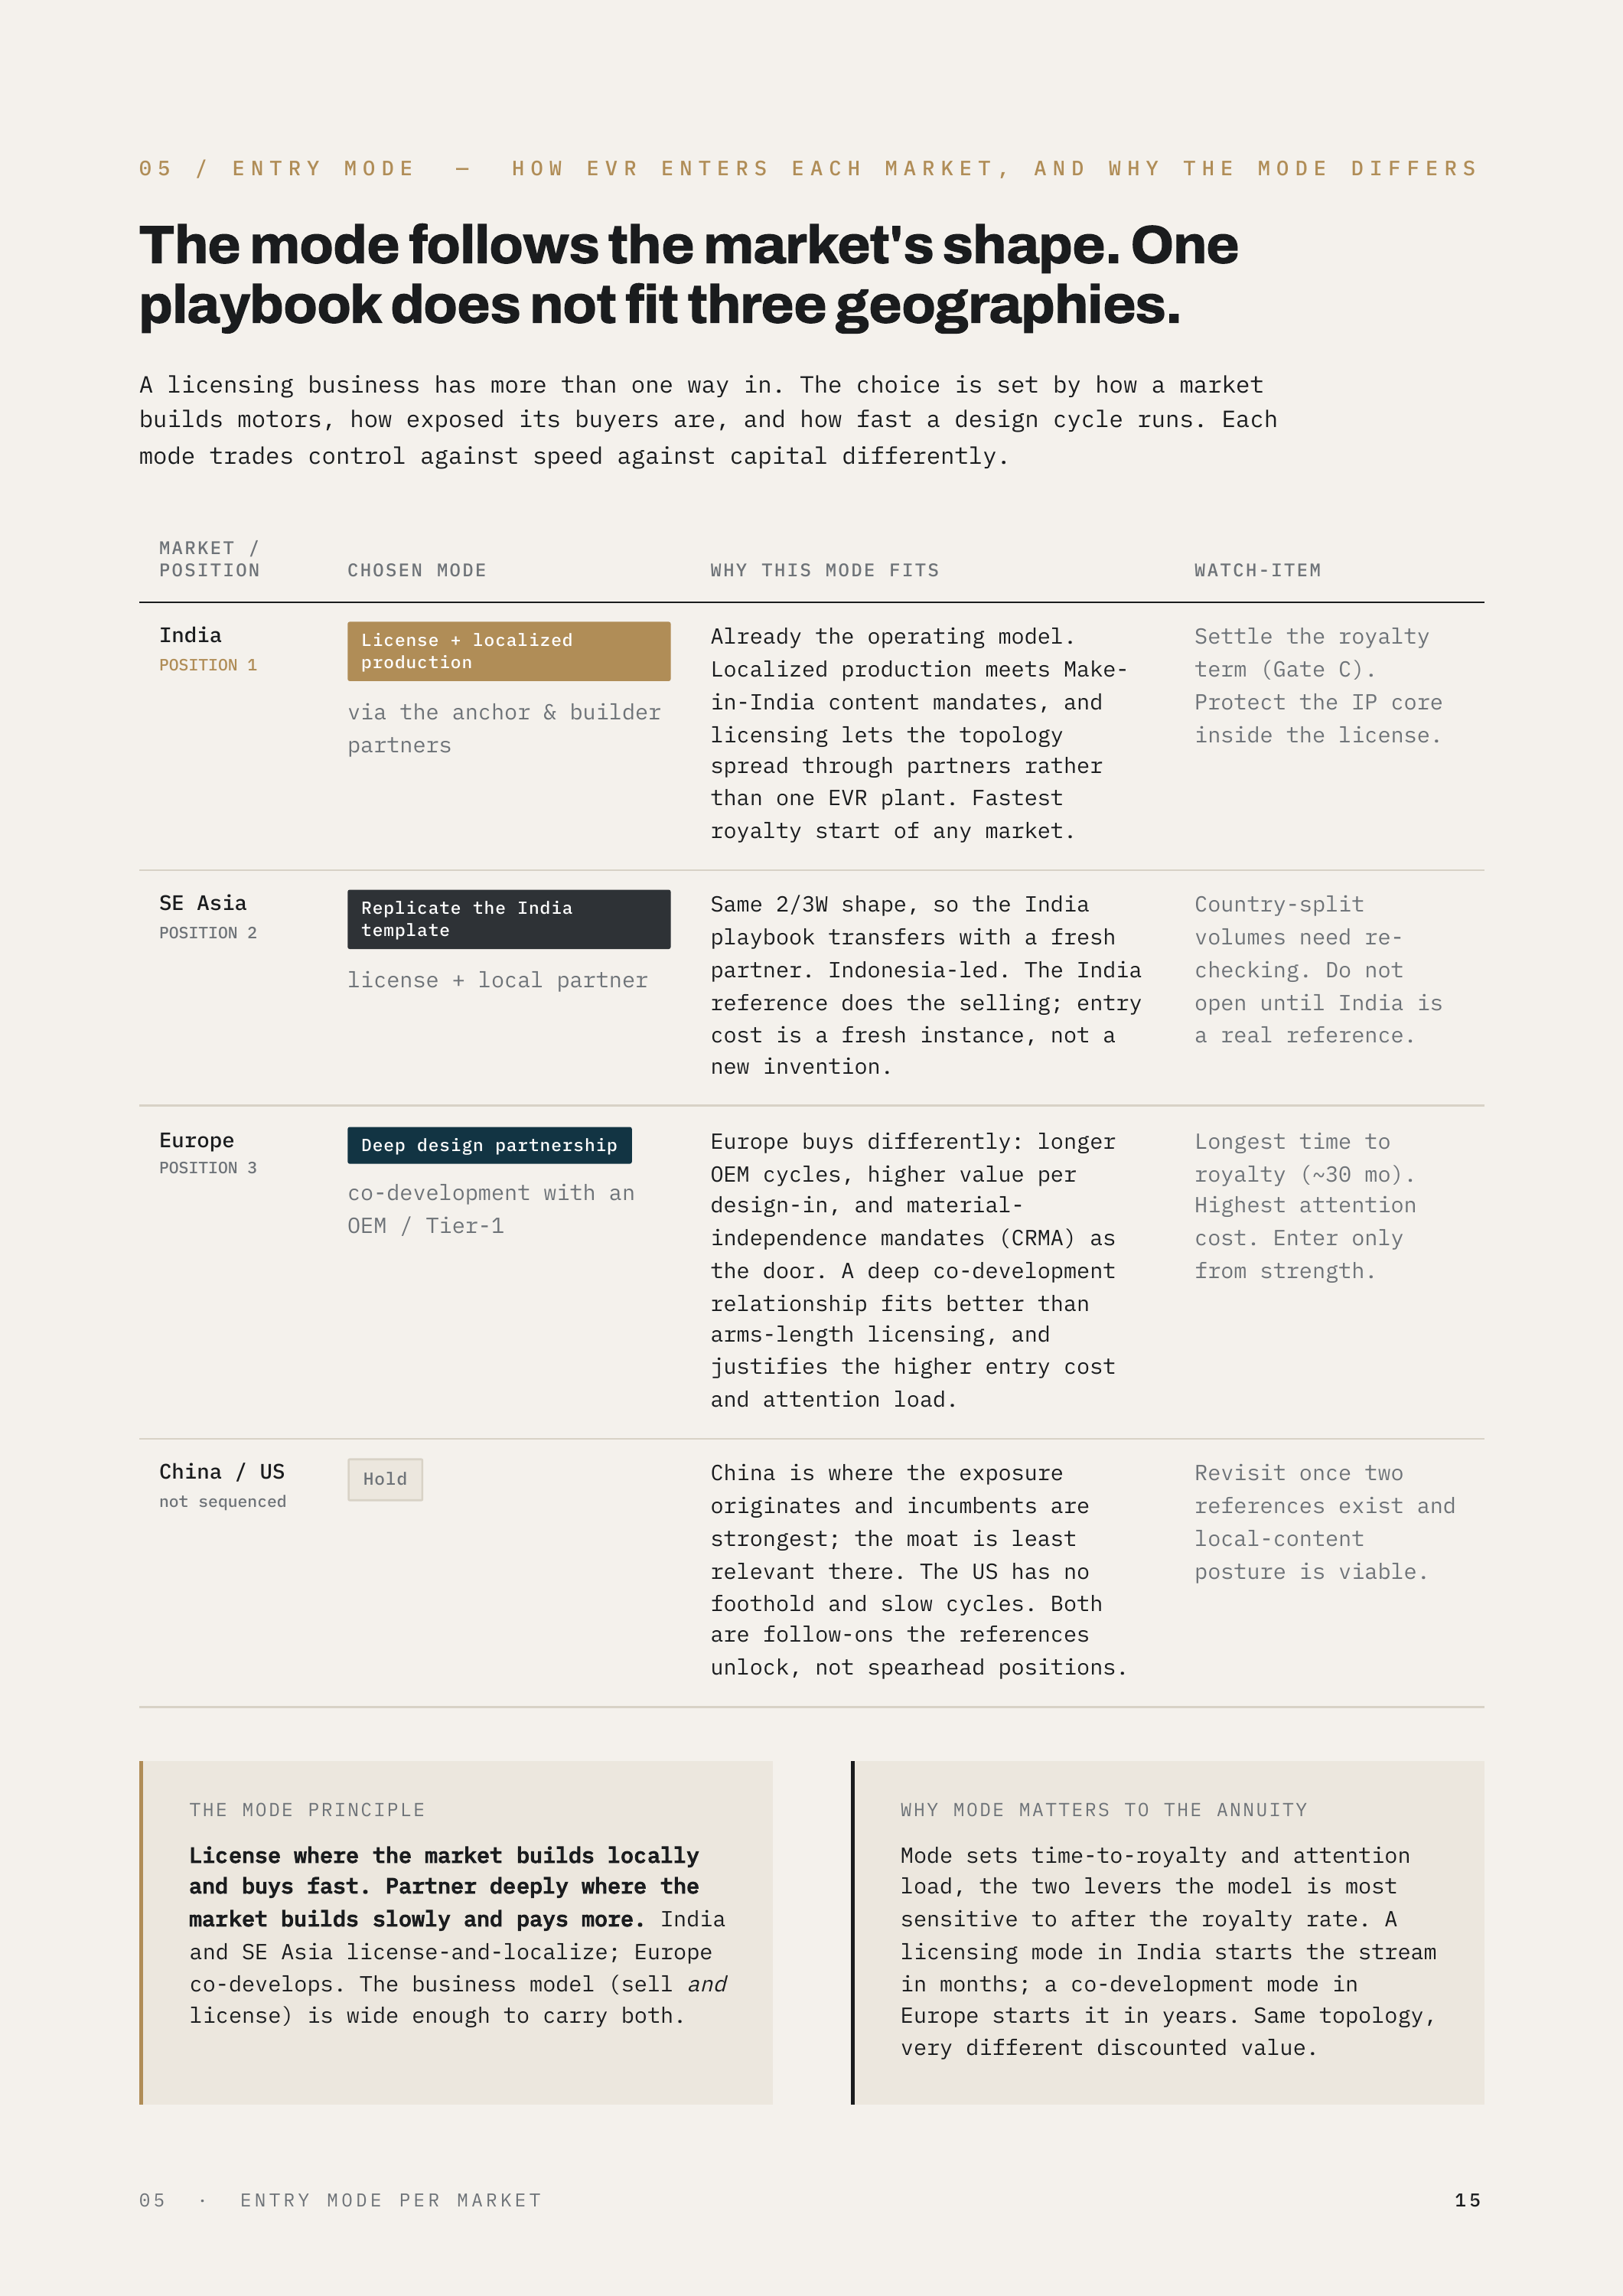
05 / ENTRY MODE — HOW EVR ENTERS EACH MARKET, AND WHY THE MODE DIFFERS The mode follows the market's shape. One playbook does not fit three geographies. A licensing business has more than one way in. The choice is set by how a market builds motors, how exposed its buyers are, and how fast a design…
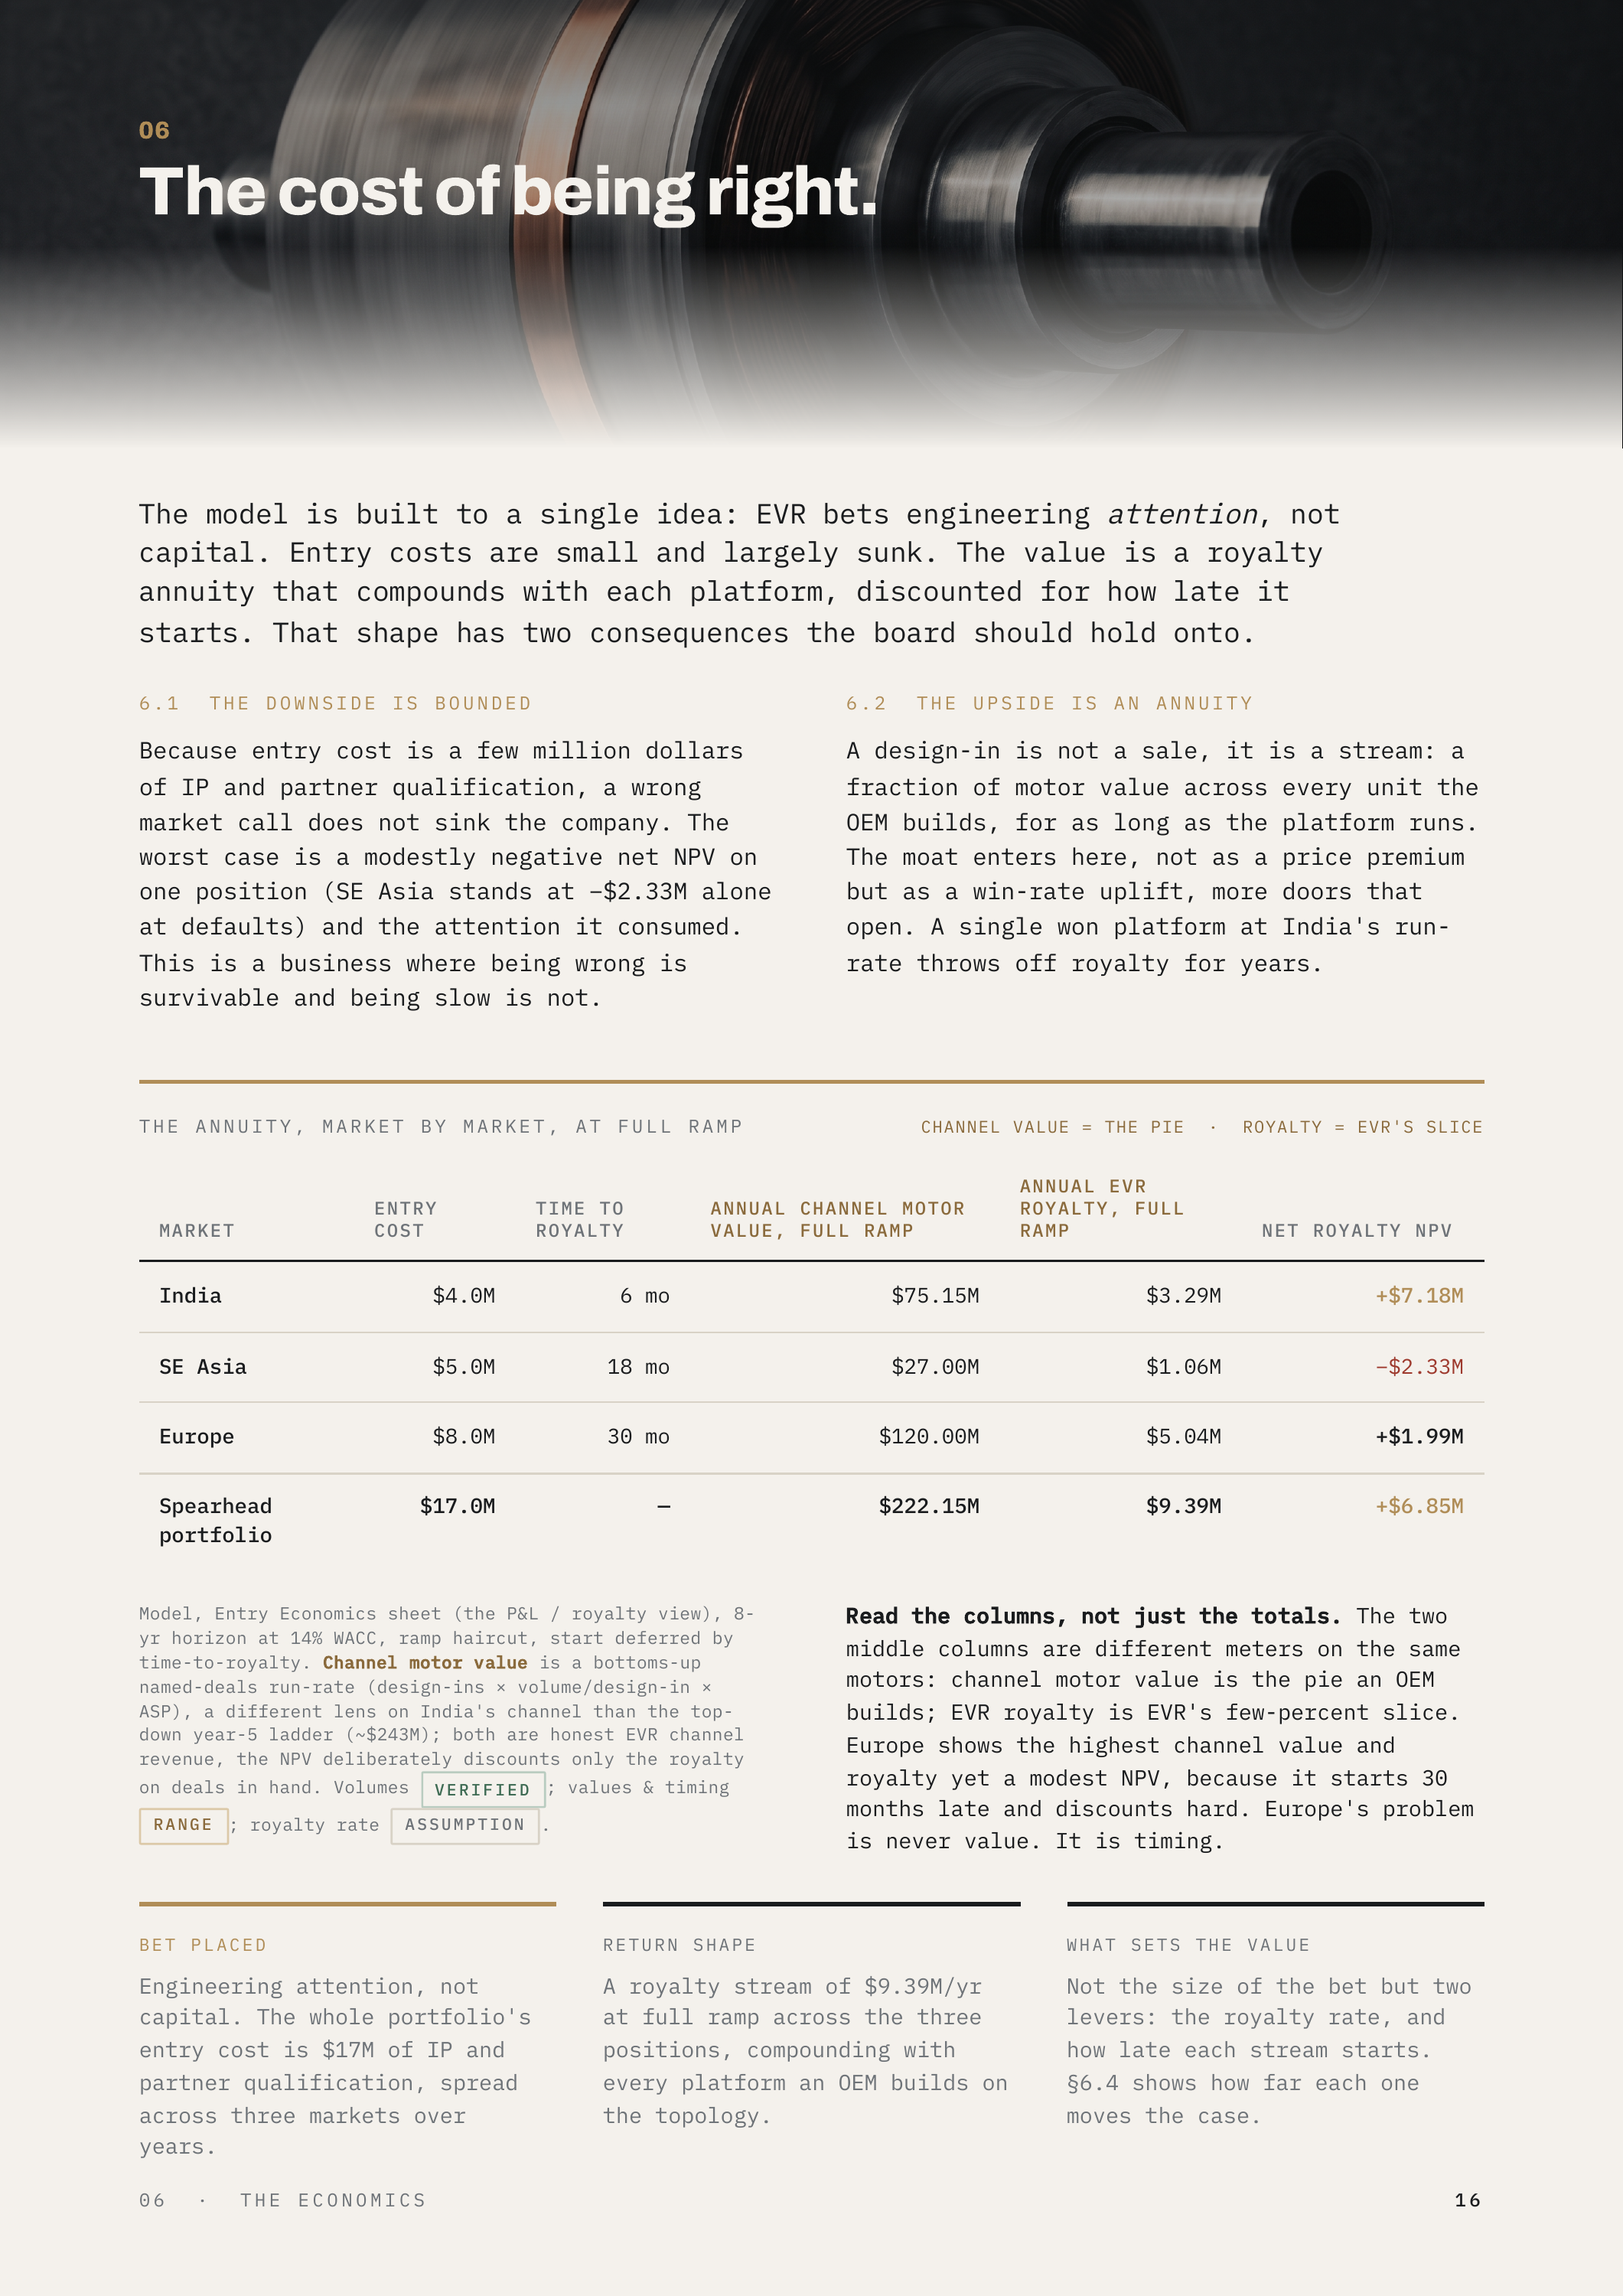
06 The cost of being right. The model is built to a single idea: EVR bets engineering attention, not capital. Entry costs are small and largely sunk. The value is a royalty annuity that compounds with each platform, discounted for how late it starts. That shape has two consequences the board should…
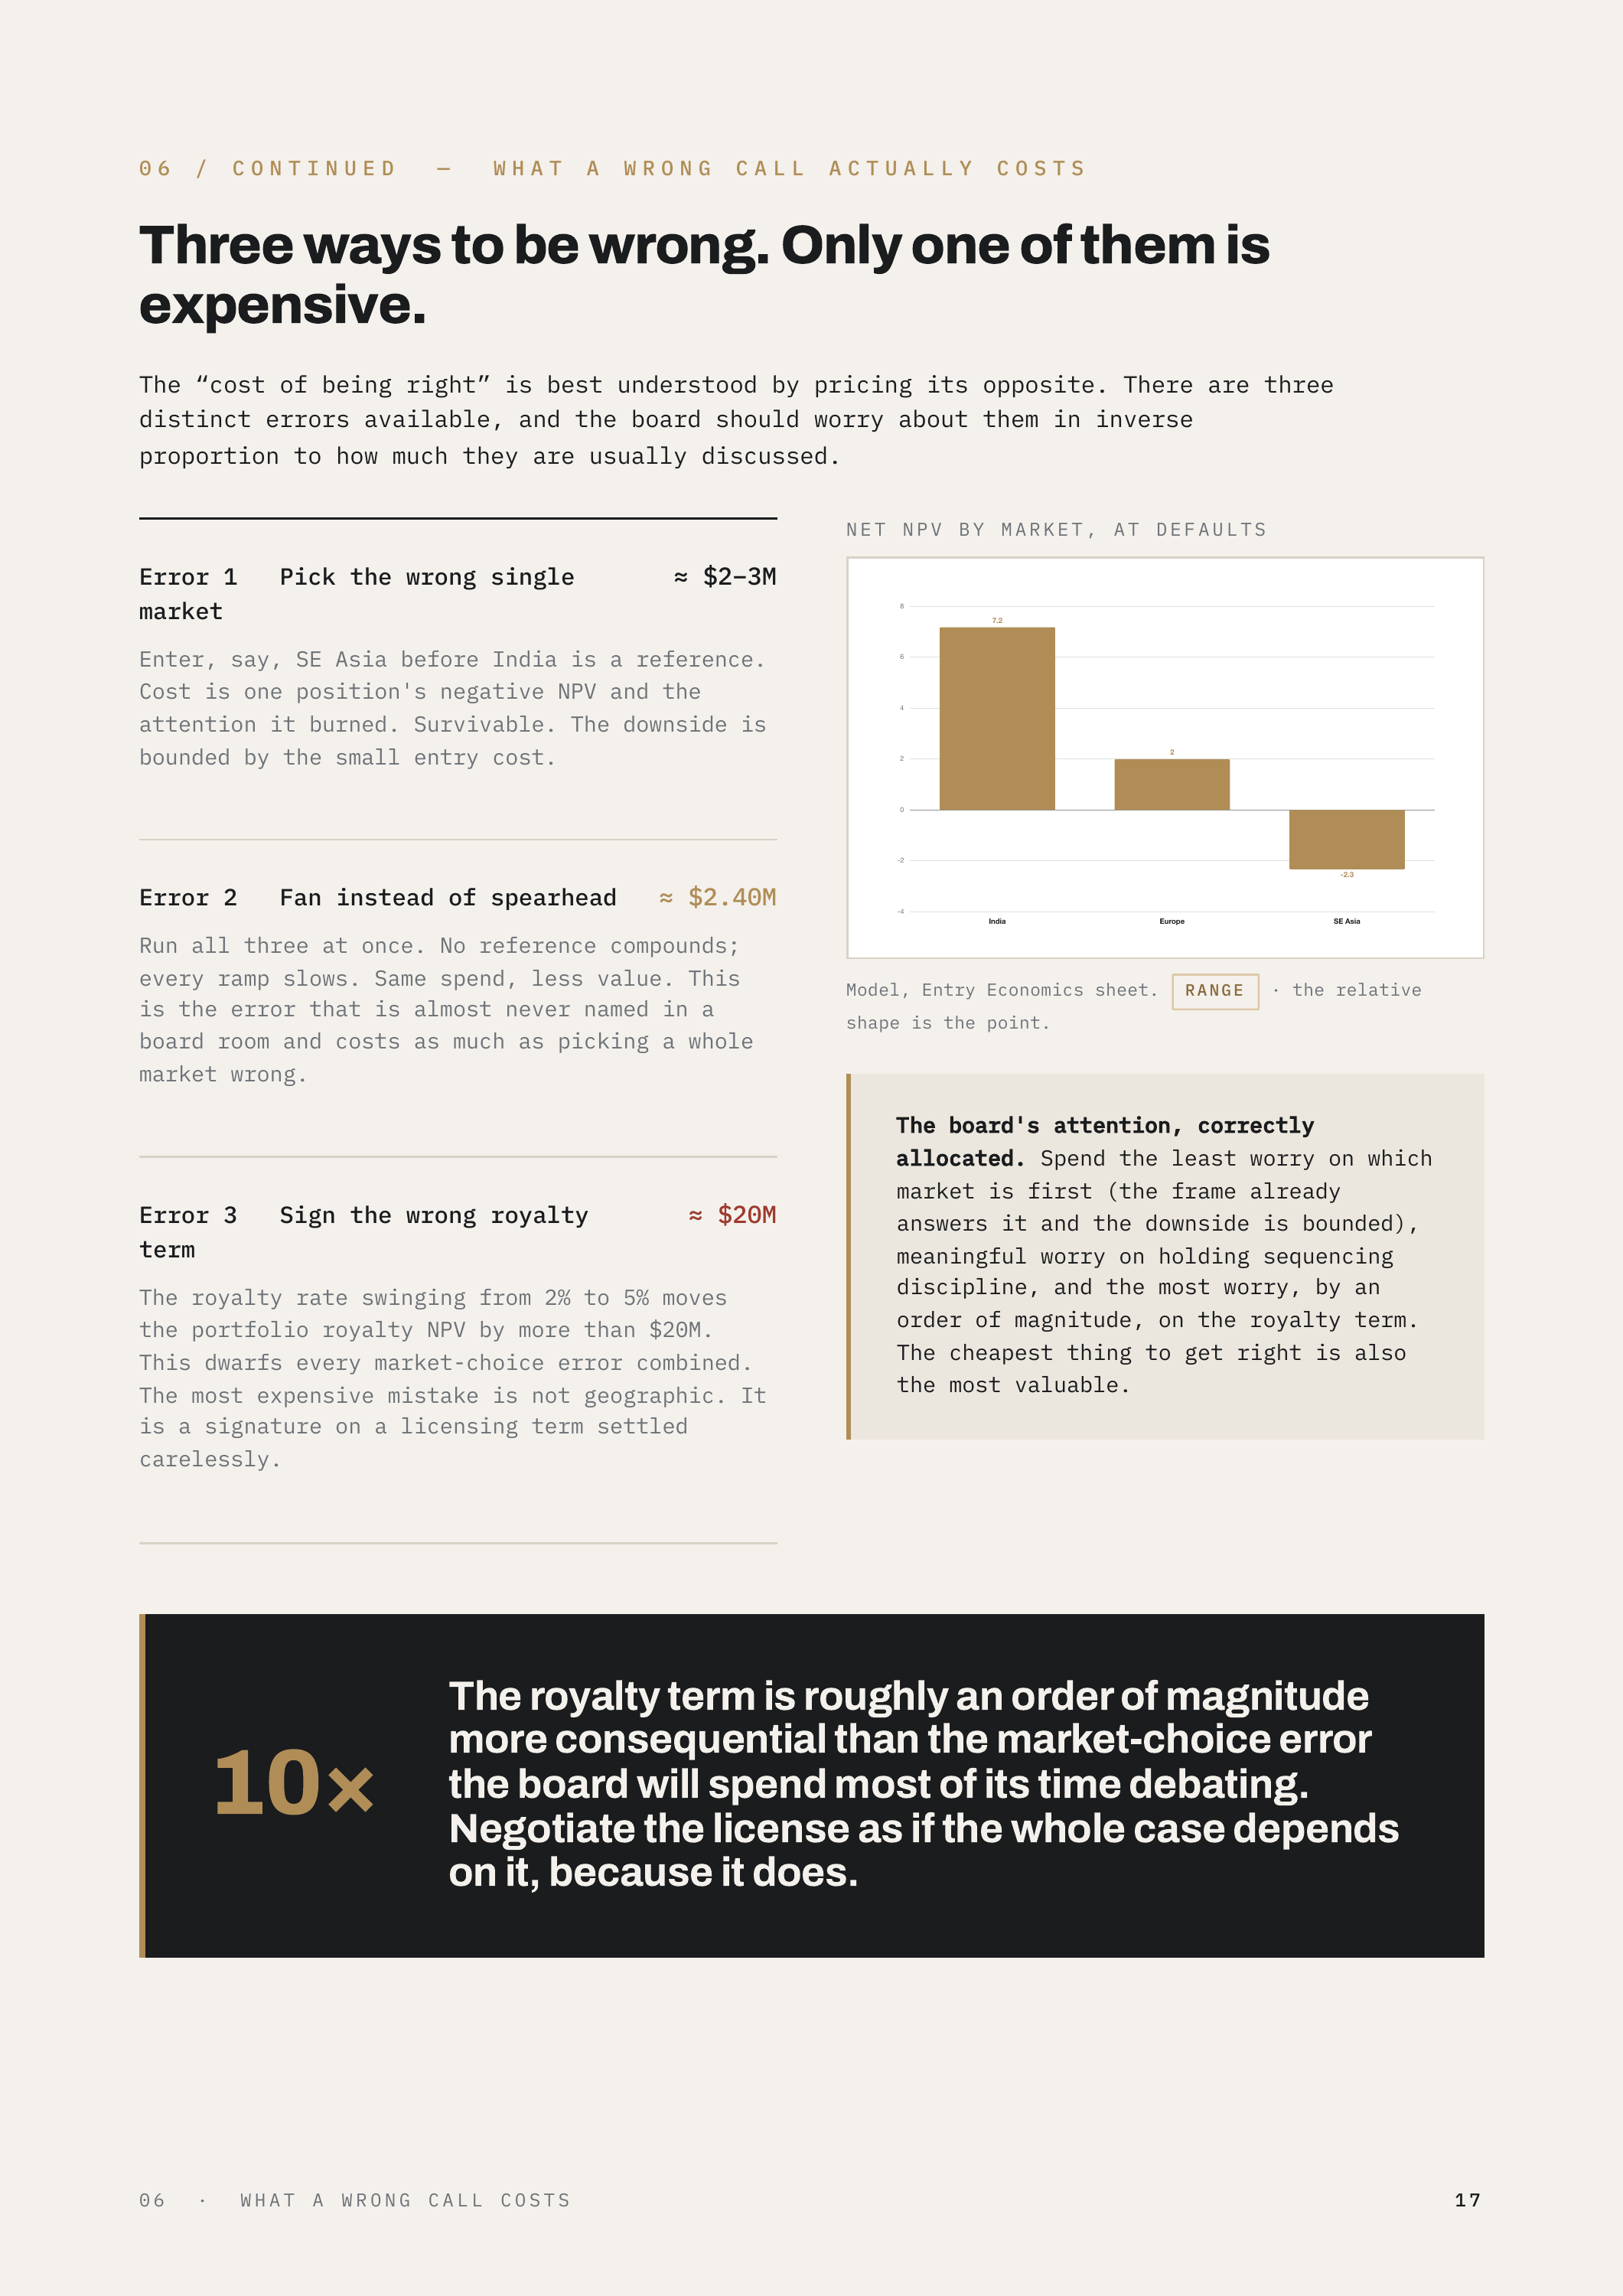
06 / CONTINUED — WHAT A WRONG CALL ACTUALLY COSTS Three ways to be wrong. Only one of them is expensive. The “cost of being right” is best understood by pricing its opposite. There are three distinct errors available, and the board should worry about them in inverse proportion to how much they are…
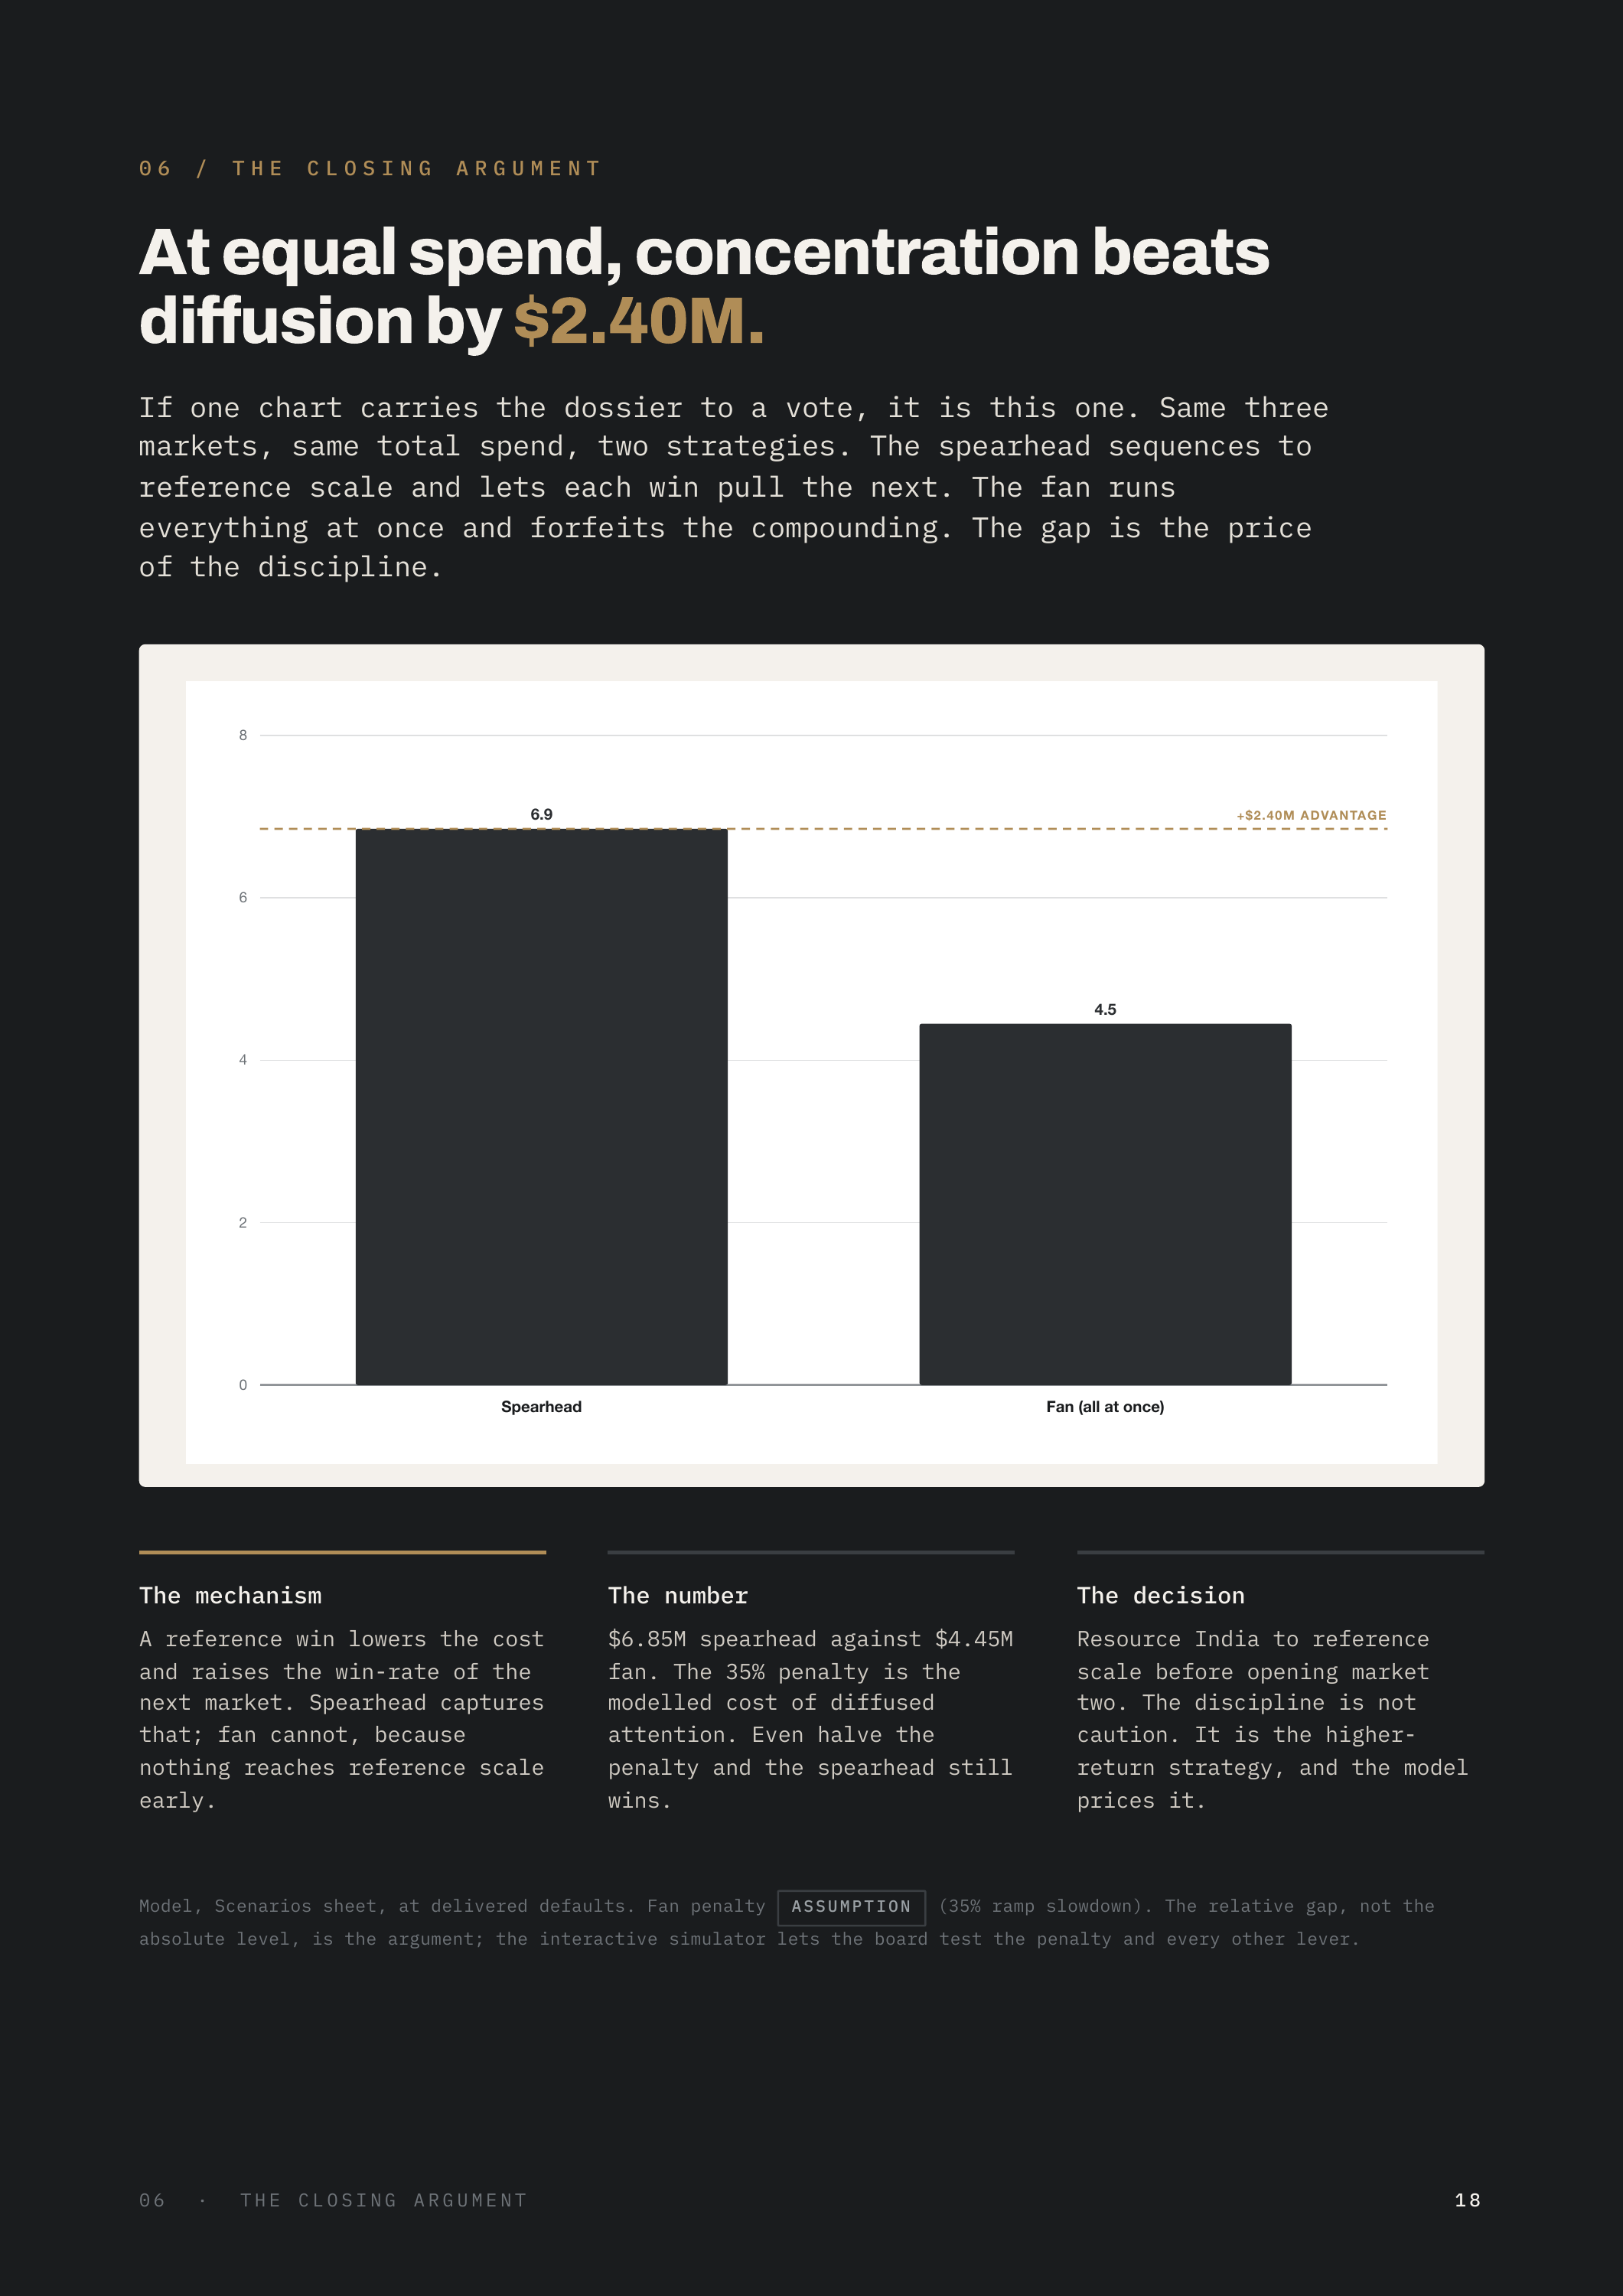
06 / THE CLOSING ARGUMENT At equal spend, concentration beats diffusion by $2.40M. If one chart carries the dossier to a vote, it is this one. Same three markets, same total spend, two strategies. The spearhead sequences to reference scale and lets each win pull the next. The fan runs everything at…
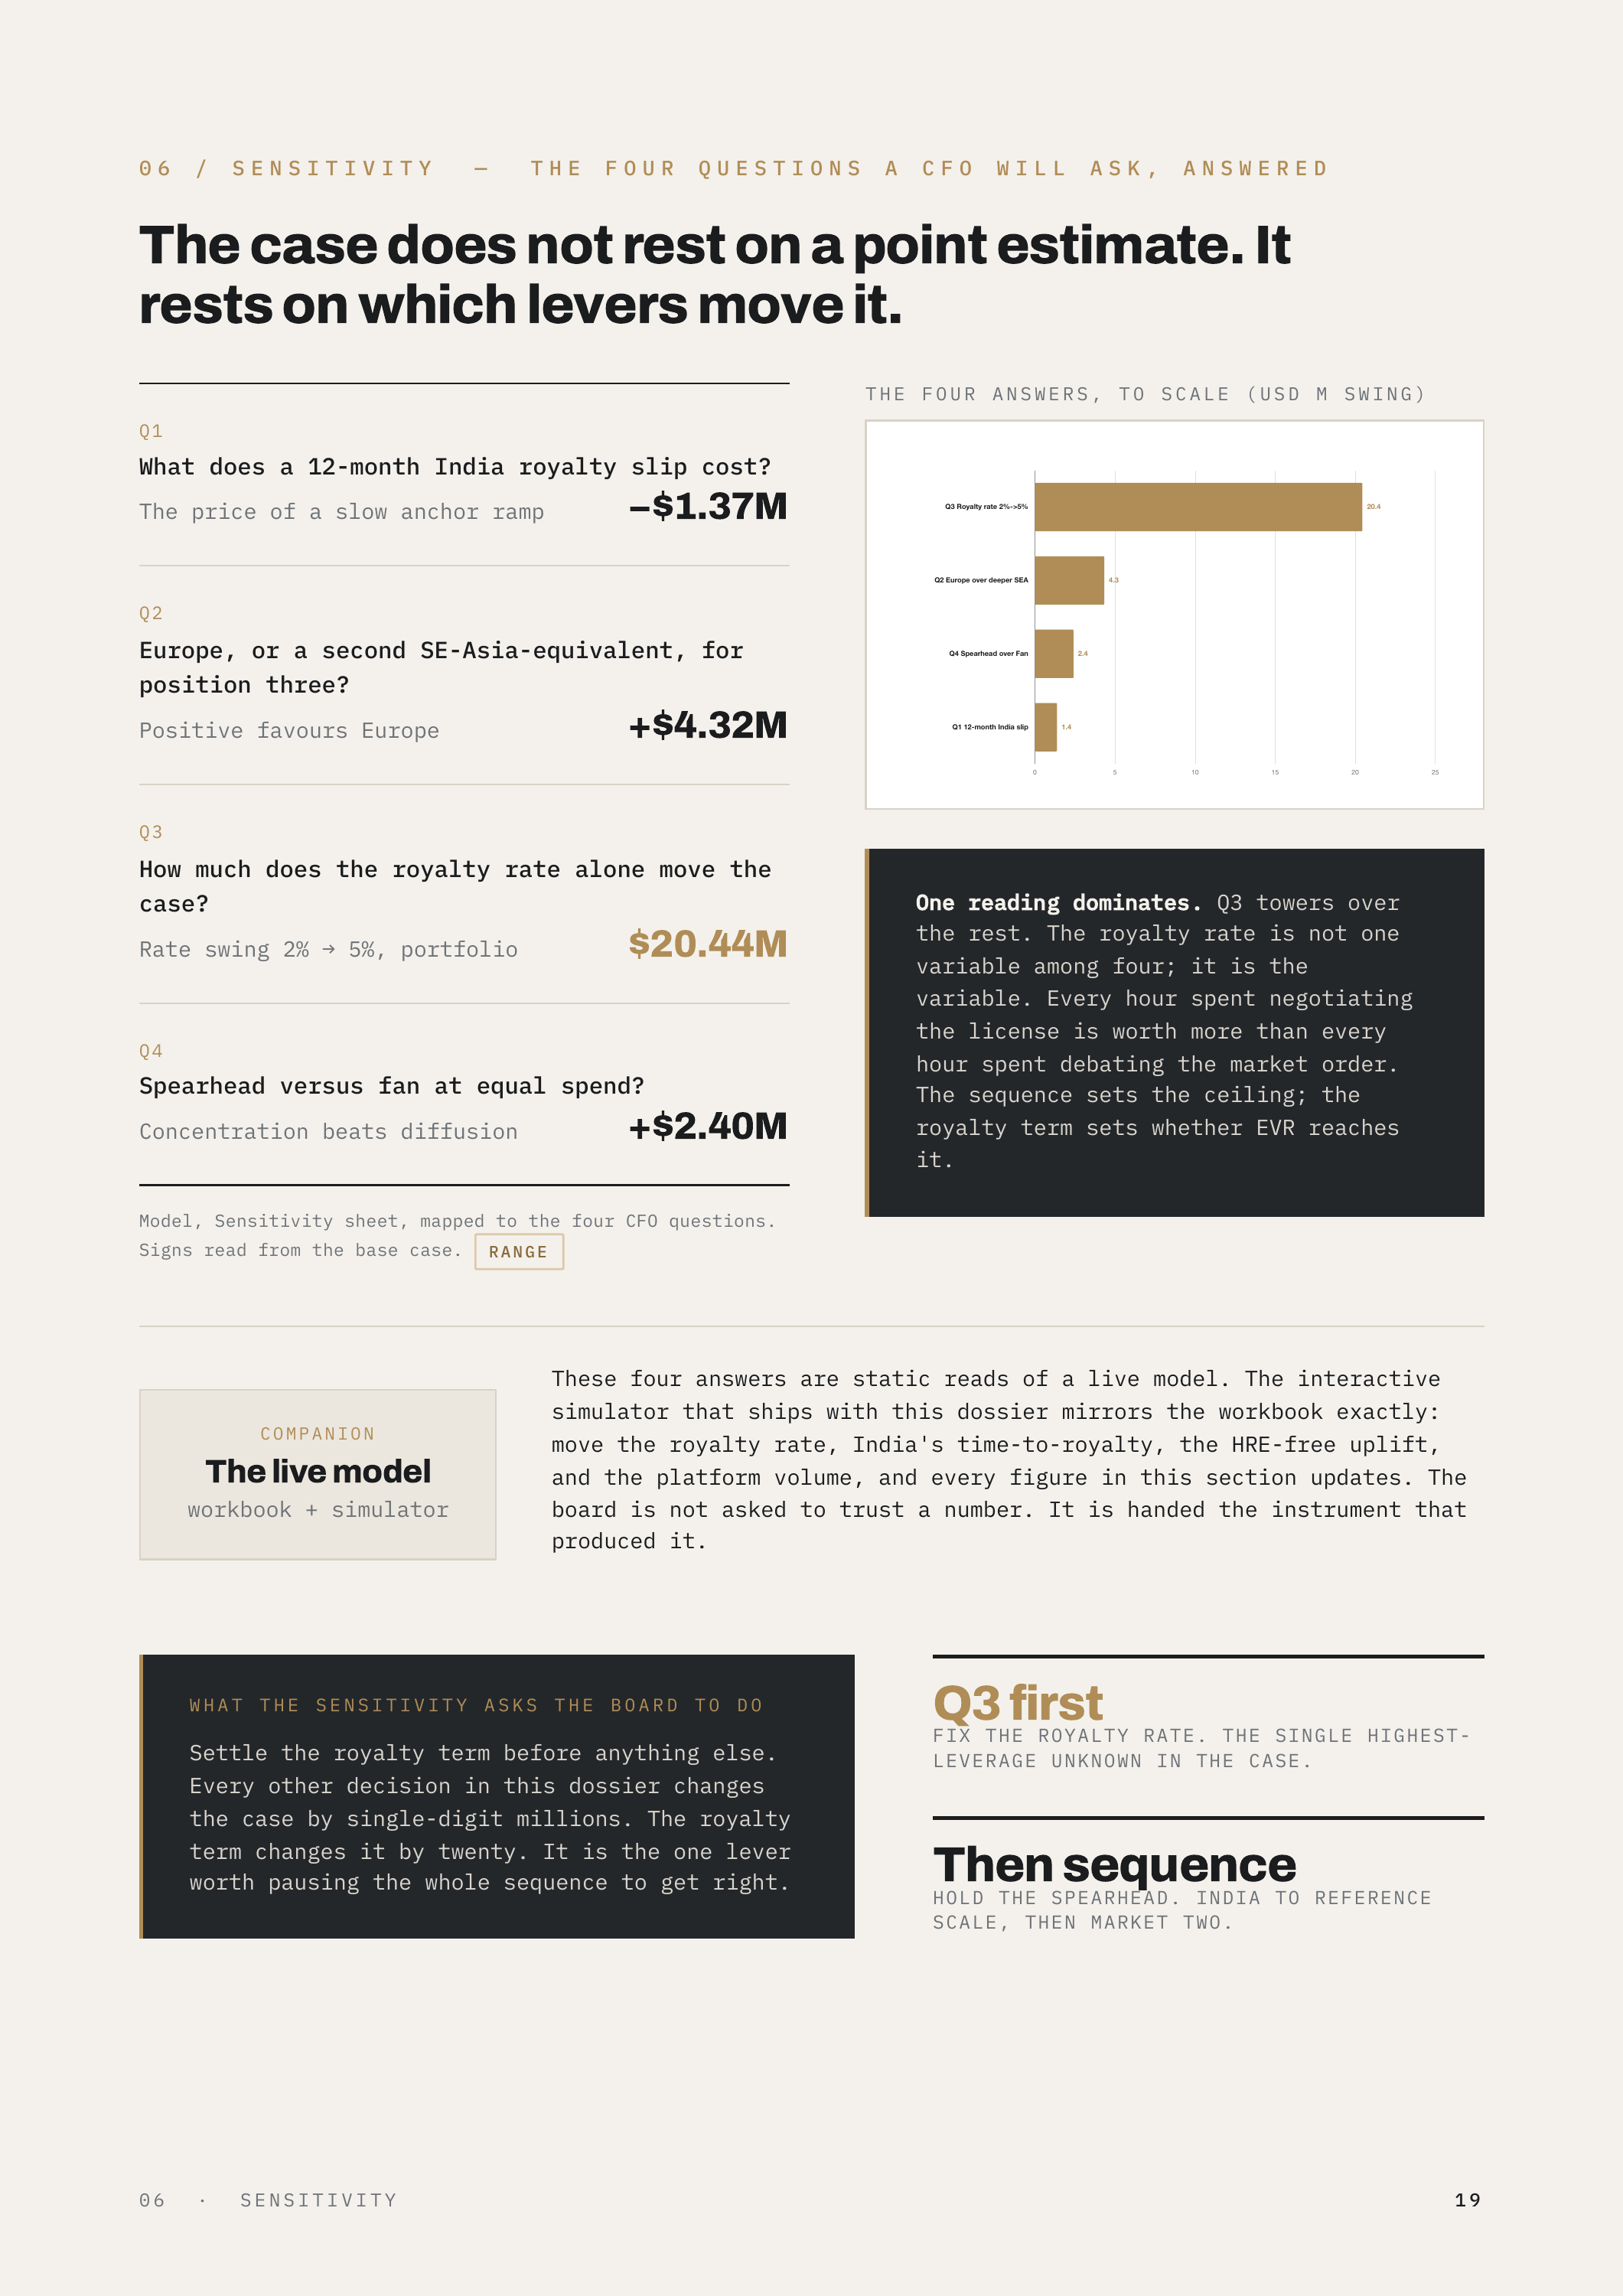
06 / SENSITIVITY — THE FOUR QUESTIONS A CFO WILL ASK, ANSWERED The case does not rest on a point estimate. It rests on which levers move it. THE FOUR ANSWERS, TO SCALE (USD M SWING) Q1 What does a 12-month India royalty slip cost? The price of a slow anchor ramp −$1.37M Q3 Royalty rate 2%->5% 20.4…
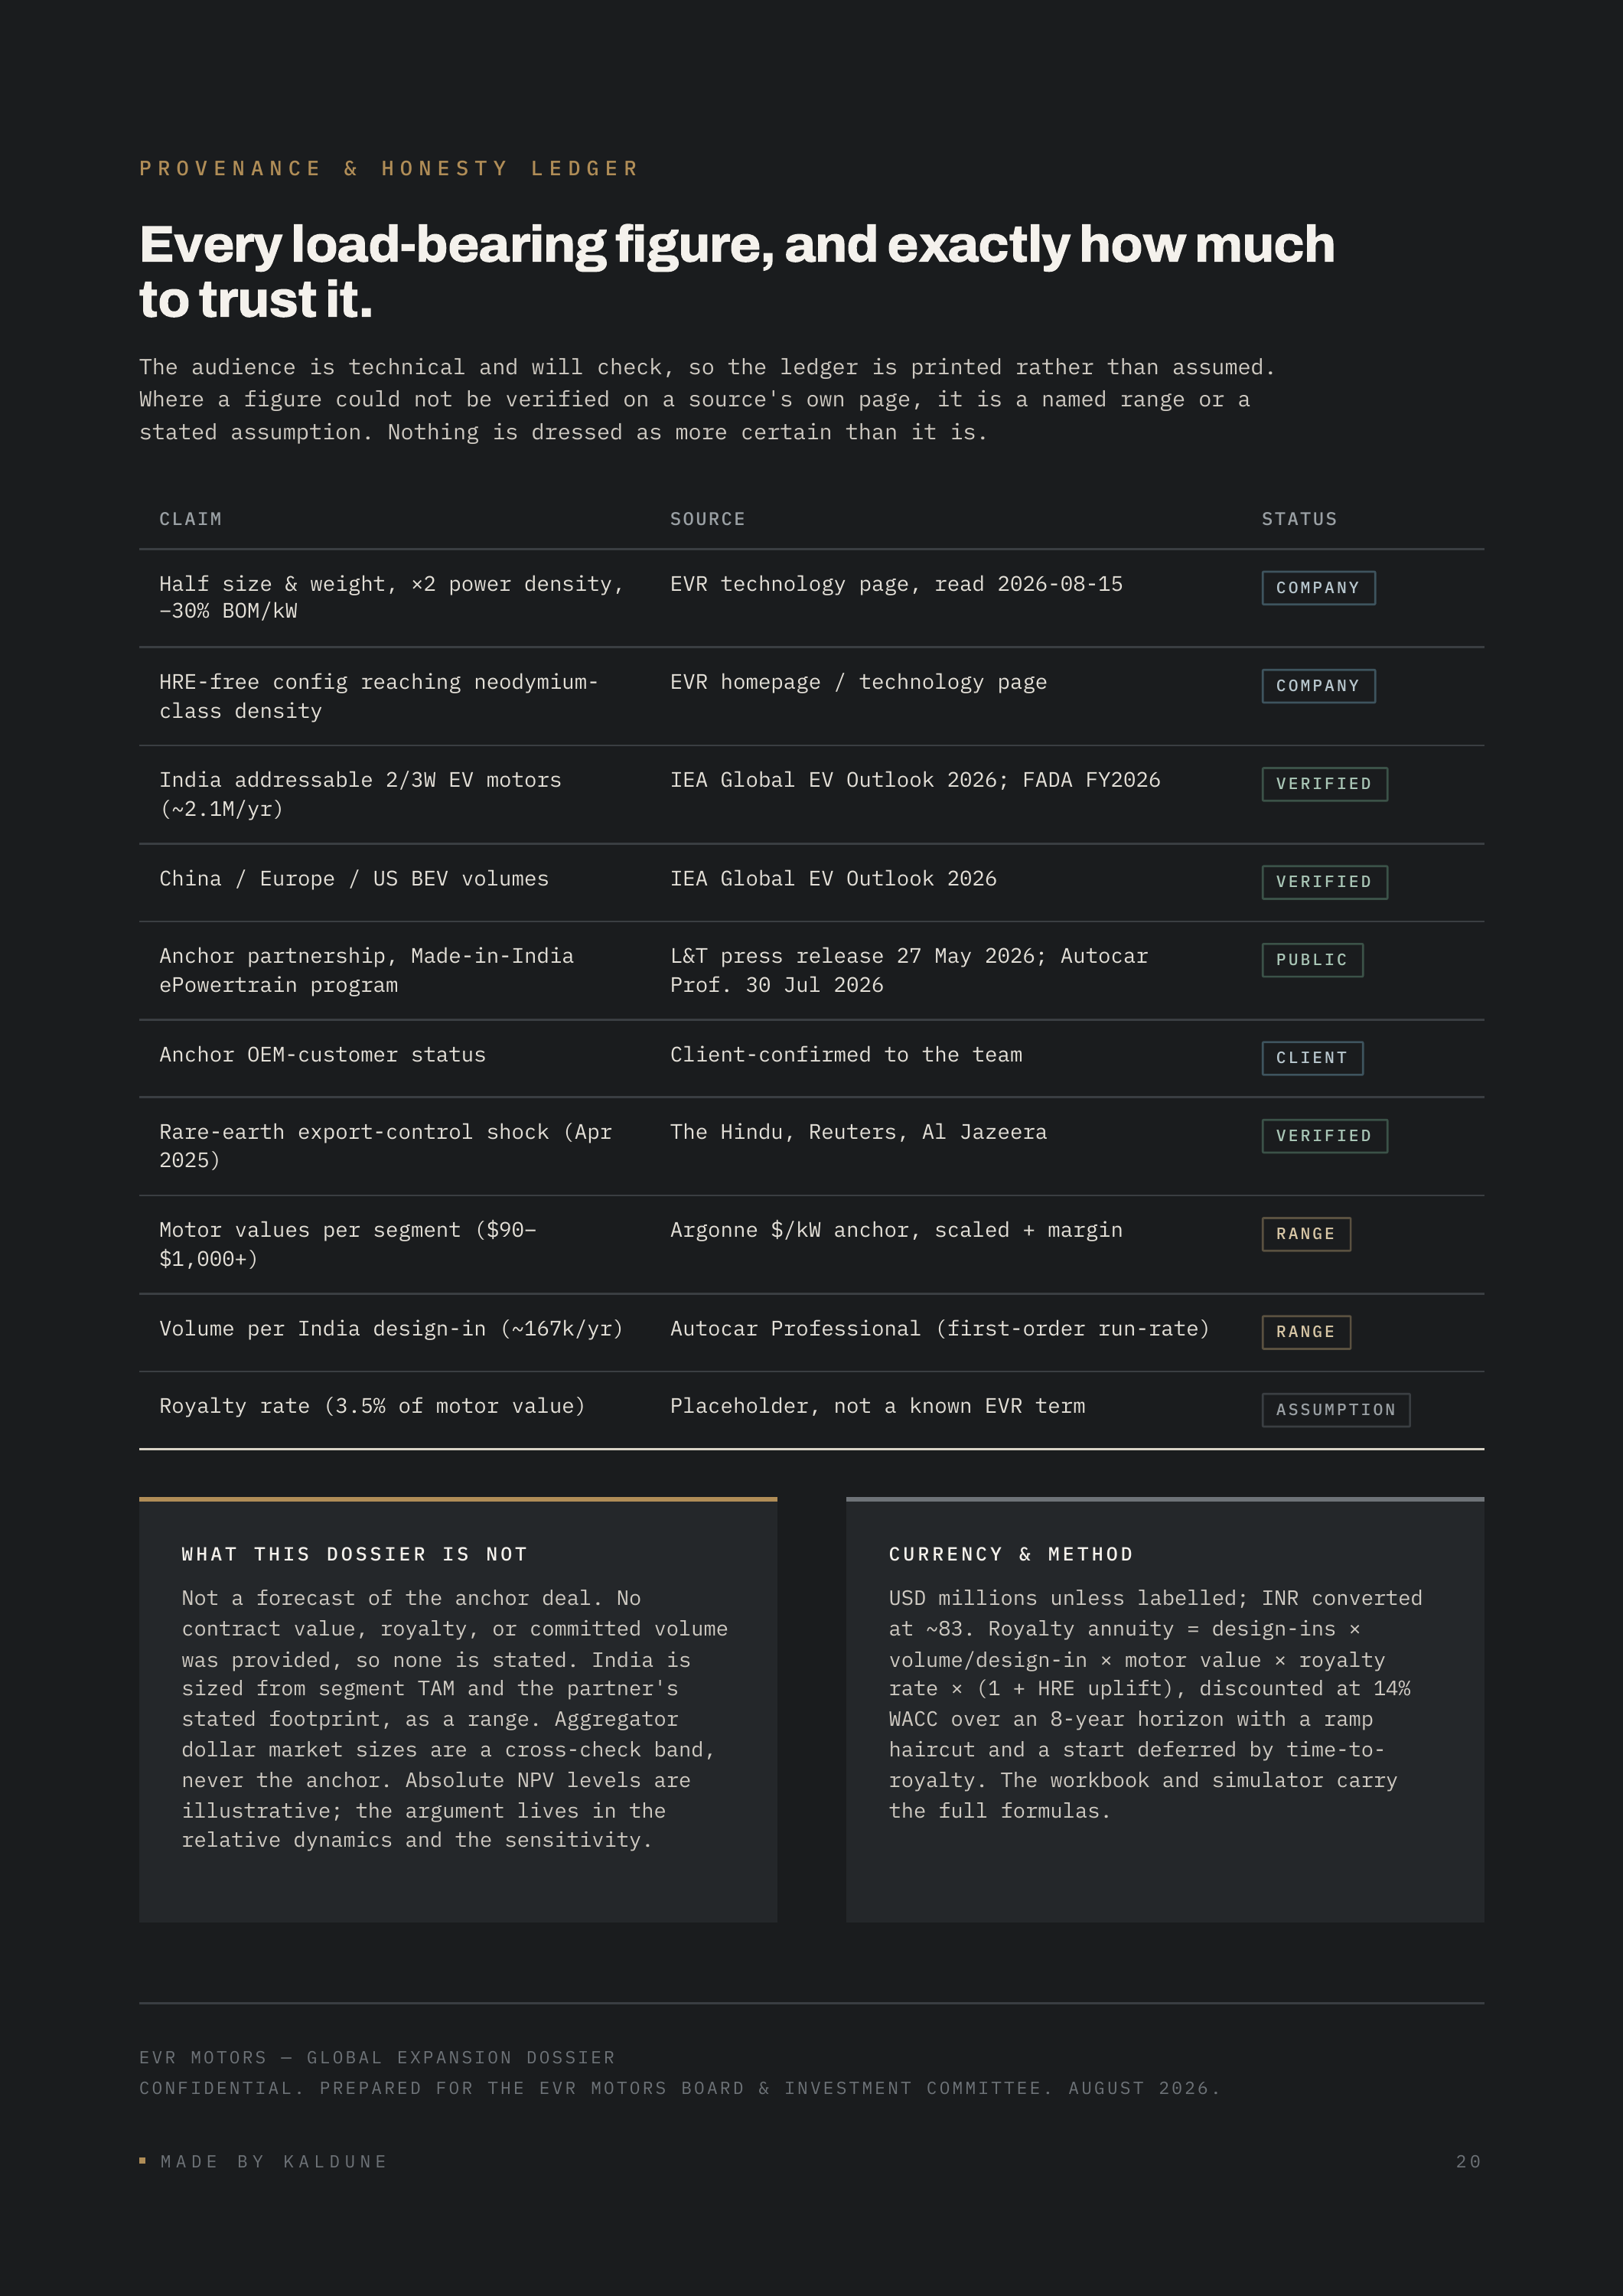
PROVENANCE & HONESTY LEDGER Every load-bearing figure, and exactly how much to trust it. The audience is technical and will check, so the ledger is printed rather than assumed. Where a figure could not be verified on a source's own page, it is a named range or a stated assumption. Nothing is…