Venture & Private Equity · Turnaround, sell or hold, settled on the numbers
Ferrum & Vale — The Decision Book
A portfolio company has missed plan seven quarters running and the partners are split three ways. The decision, settled on the numbers.
The brief, verbatim
I'm a partner at a lower-middle-market PE firm. Three years ago we bought Ferrum & Vale, a $46M specialty industrial distribution business (fictional company, real discipline), at 6.8x. It has missed plan seven quarters straight: EBITDA down from $6.8M to $4.9M, two of the five branch managers gone, our best supplier flirting with going direct. My partners are split three ways: fund a real turnaround, sell now and eat the mark, or hold and ride it out. Build me the decision book: the honest diagnosis of what is actually broken versus what is cyclical; the turnaround priced lever by lever with the odds stated like an adult; what a sale TODAY realistically fetches and from whom; what holding costs us in fund math and reputation; and a simulator where I can move the recovery assumptions and watch what each path returns, because this argument has eaten three Mondays and I want it settled on the numbers. End on a recommendation with a spine.
What the studio made
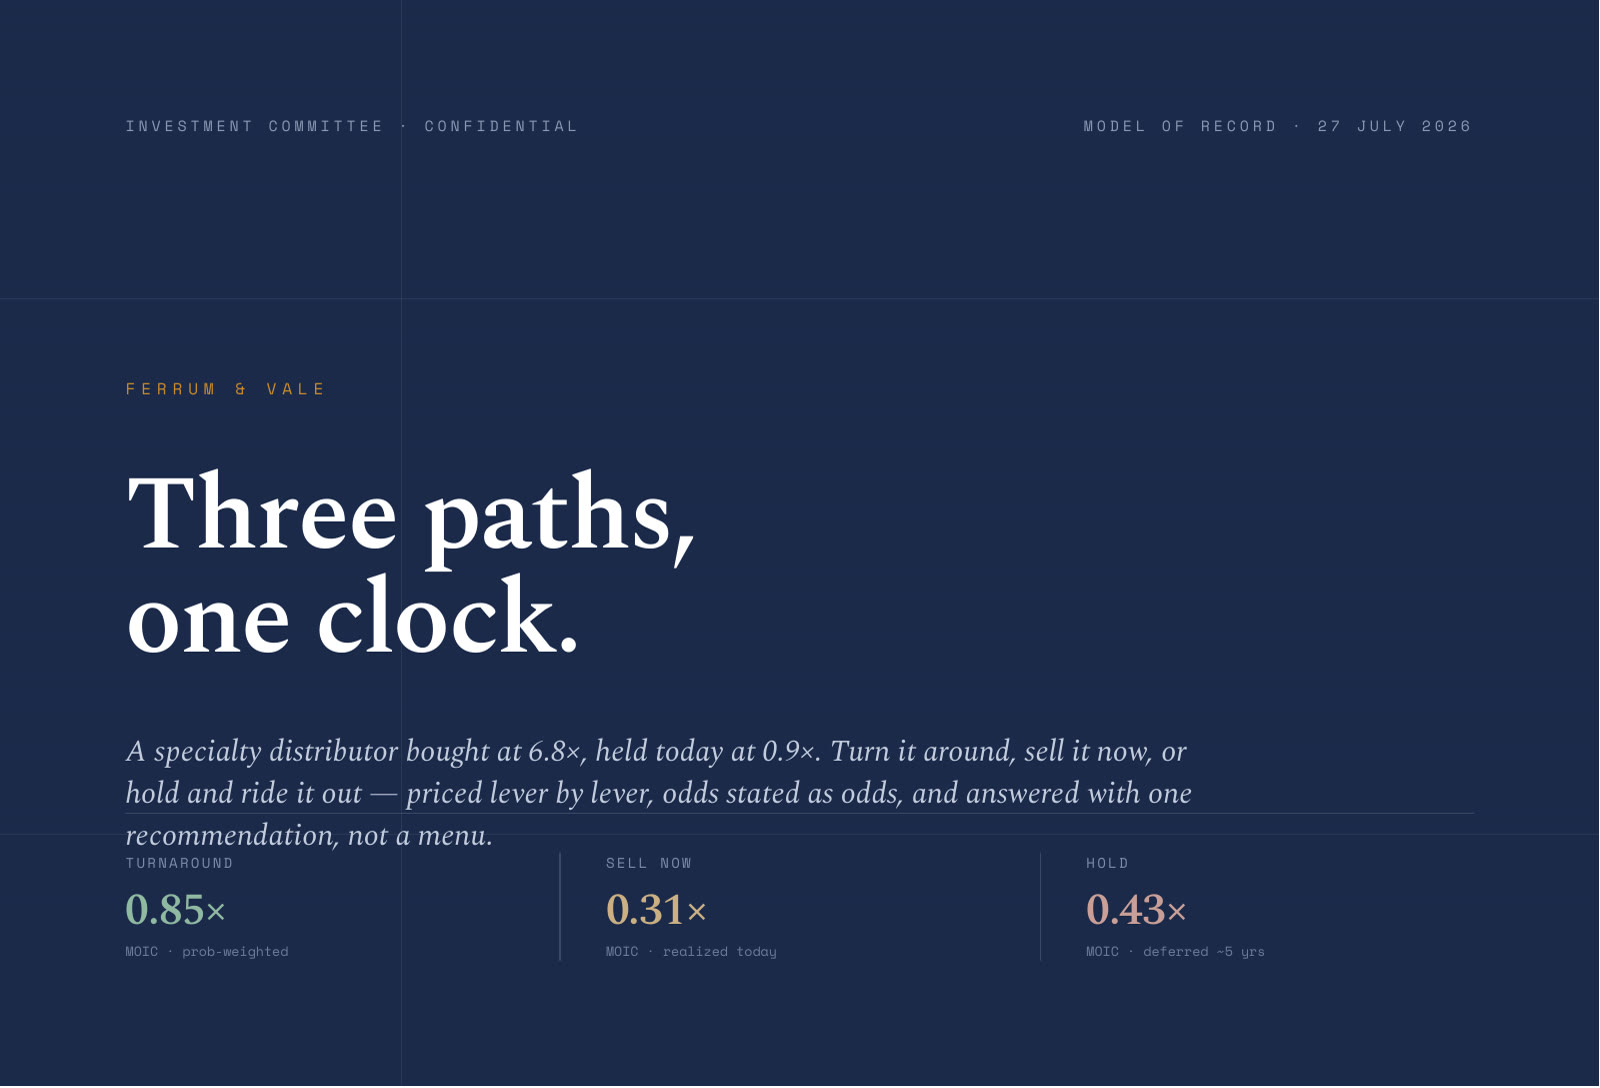
A twelve-page investment-committee decision book: the honest diagnosis of what is self-inflicted versus cyclical, the EBITDA bridge, the forward risk of the anchor supplier going direct, the turnaround priced lever by lever with stated odds, what a sale today really fetches and from whom, the cost of holding on the fund's clock, and a recommendation with a spine. Beside it, a live simulator and a working model where every path's returns move with the recovery assumptions, book, simulator and model in agreement.
The finished work
Build your own
You have something to build. Brief the studio in plain English and watch a room of specialists build it.
Get early access